The market mirror
Resilient jobs, costly capital: looking beneath the AI rebound
Hiring and chip demand offer support, but inflation, financing costs and uncertain AI returns complicate the recovery. A reading on evidence, expectations and the urge to react.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · November 9, 2026 at 7:00 AM · New York
U.S. Bureau of Labor Statistics
October U.S. payrolls rise by 165,000 ↗
The Bureau of Labor Statistics reported 165,000 additional October jobs, unemployment at 4.1%, and upward revisions totaling 84,000 for August and September. Hourly pay rose 0.4% in the month. Employment and income can support household purchases and company revenues; stronger wages can also raise costs where productivity or pricing cannot offset them. The increase in involuntary part-time work cautions against treating the headline as proof that every household is comfortable. This release describes labor conditions, not a stock-market forecast.
Federal Reserve
Fed holds rates while stressing elevated inflation ↗
The Fed's October 28 decision kept its policy range at 3.75%–4%, with two members preferring an increase. Its statement described strong activity and elevated inflation. That combination matters because robust demand can support earnings while persistent inflation keeps borrowing expensive. A policy hold did not promise cheaper capital. Maintaining ample bank reserves concerns the functioning of the banking system; it does not mean every company can refinance cheaply or that equity valuations are protected.
Reuters via MarketScreener
Asian shares recover after AI selloff; rate-hike bets remain firm ↗
Reuters reported an early Monday recovery in Asian shares and slightly positive U.S. equity futures after Friday's Wall Street rebound. It also described the prior week's AI-related selling and concerns about data-center regulation after the U.S. midterms. Those are reported market reactions and concerns, rather than proof of a particular future regulation. The report put futures-implied odds of a December rate increase near 80%; that is a dated market estimate, not a Fed commitment. With inflation data and technology earnings still ahead, the rebound alone cannot establish improved profits or cheaper valuations.
Tom's Hardware
AMD's data-center growth contrasts with weaker gaming sales ↗
Tom's Hardware reported AMD's record third-quarter revenue of $13.377 billion, with data-center sales rising 97% to about $8.55 billion while Client and Gaming sales fell 8%. These results show that meaningful infrastructure demand can coexist with weakness elsewhere in the same business. Management's approximately $17 billion fourth-quarter revenue outlook remains guidance. Strong supplier sales support a demand case, but do not establish that customers will earn adequate returns on their spending or that the supplier's shares are attractively valued. We do not have a complete valuation or consensus comparison here.
Reuters via CNBC
Oil falls on Iran diplomacy hopes despite shipping attacks ↗
Reuters, carried by CNBC, reported Brent at $97.57, down 0.75% at 10:11 GMT, after a 16% decline the previous week. Trump's restraint on fresh Iran attacks supported hopes for diplomacy, while attacks near Hormuz kept shipping risk alive. Lower sustained fuel costs could improve transport margins and household spending power, while reducing producers' revenues. The report also noted physical-market weakness: falling oil could reflect softer demand as well as reduced supply fear. A price decline does not itself verify peace, restored shipping security or an economy-wide inflation improvement.
Reuters via MarketScreener
China trade poll points to export strength and domestic imbalance ↗
A Reuters poll projected October Chinese export growth of 33.5% and import growth of 32%, ahead of Tuesday's data release. These are forecasts, not published October results. The report contrasted AI-linked shipments with weak domestic consumption and contracting factory new-export-order gauges. Strong exports could support manufacturers and suppliers, but front-loaded shipments or trade restrictions could make that strength less durable. Weak household demand also limits the read-through to global consumer businesses. The actual trade release and subsequent orders will matter more than treating the poll as a completed outcome.
A three-card reflection
01Backdrop
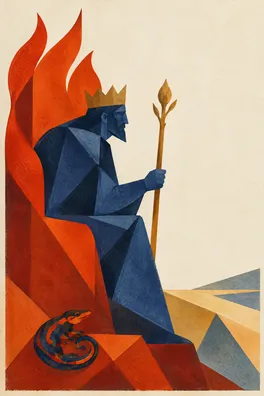
King of Wands
Reversed
The reversed King of Wands, in Backdrop, asks what happens when an ambitious story outruns accountable execution. Its established meaning includes impulsive leadership, unrealistic expectations and promises without follow-through. Here it is a lens for examining the distance between an investment narrative and the work required to turn spending into earnings. It is not a judgment about any named executive and supplies no evidence about the economy.
The evidence supports a mixed assessment. Hiring provides an income base for demand, and AMD's results demonstrate real activity within the AI buildout. Yet high spending is a cost to the buyer before it becomes a return. If projects face delays, expensive financing or weak utilization, suppliers' current sales can coexist with customers' disappointing future cash generation. Higher interest rates can also reduce the amount investors are willing to pay today for profits expected far in the future. That valuation channel is different from a fall in current revenue.
A practical reading is to ask what blocks the promised result. For an infrastructure story, distinguish demand for equipment from profitable use of that equipment; for a consumer story, distinguish a job gain from affordable living costs. Write one missing piece of evidence beside each confident claim you encounter. The blind spot would be to turn healthy skepticism into a belief that every ambitious plan must fail. Strong execution and improving productivity could justify optimism, but the confidence should grow with evidence rather than the forcefulness of the promise.
02Pressure point
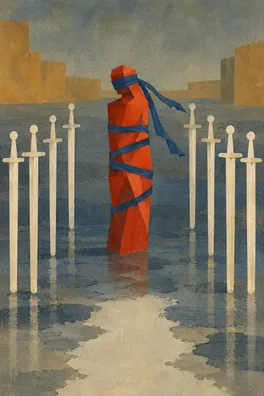
Eight of Swords
Reversed
The reversed Eight of Swords, in Pressure point, describes constraints loosening and a choice becoming visible. In this position, the tension is the temptation to mistake relief from one constraint for freedom from all of them. Lower oil prices and a rebound in shares may loosen an immediate sense of danger. They do not automatically remove inflation pressure, refinancing costs or uncertainty about AI project returns.
There is a plausible constructive path: a durable easing in energy costs could leave households more room to spend and businesses more room in their margins, while resilient employment supports sales. If inflation also moderates without a sharp demand setback, the conflict between earnings support and restrictive financing could ease. The competing explanation is less comfortable. Oil might be falling partly because demand is weakening, while inflation elsewhere remains persistent. In that case, the same headline could accompany pressure on revenues and continued expensive credit. Neither path is established by this snapshot.
Reclaiming choice means refusing the false deadline created by fear of missing out. You can decide which question deserves attention before deciding whether a price move means anything for your own circumstances. Record one piece of evidence that would strengthen the constructive view and one that would weaken it, then take a small step such as reading the original release instead of another reaction thread. An exit from a crowded narrative need not become a contrary narrative adopted with equal certainty. A changed perspective remains useful only while it stays open to correction.
03Grounded response
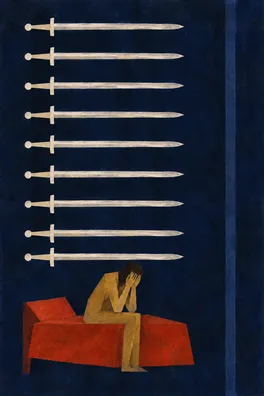
Nine of Swords
Reversed
The reversed Nine of Swords, in Grounded response, has two possible directions: worry can ease through honest conversation, or become more hidden and burdensome. That ambiguity matters after a selloff and rebound. Feeling calmer may mean you have understood the uncertainty more clearly; it may also mean a rising screen has temporarily silenced an unresolved concern. The card invites examination of that difference, not a forecast of recovery.
Make the concern specific enough to discuss. Instead of saying that the market feels unsafe, name the issue: perhaps your attention is trapped by AI headlines, you do not understand how borrowing costs affect a business, or a volatile position is taking more emotional space than you expected. Ask a trusted person for a defined kind of support, such as listening while you explain the reasoning, or helping identify an assumption you have treated as fact. Agreement is not the only useful response; a clear question may be more valuable than reassurance.
For the next information session, separate reported facts, observed prices and your interpretation into three short notes. Add the time horizon relevant to the question, because an overnight recovery and a multi-year earnings case answer different things. Set a planned time to revisit the evidence instead of repeatedly checking for emotional relief. If concern remains, review your own risk tolerance and the questions that require qualified advice. The aim is not to suppress discomfort or force confidence, but to make uncertainty discussable before it drives a hurried decision.
My qualified view is that the evidence offers more support for continued economic activity than for declaring the equity-market adjustment finished. Employment and reported infrastructure sales are meaningful supports. Inflation, financing costs and uncertain returns on investment can nevertheless compress valuations even while some businesses grow. A short-term rebound can reflect changing risk appetite without resolving that slower earnings-and-capital-cost debate. The snapshot does not establish how fully these risks are already reflected in share prices.
The reversed King of Wands brings the question of execution into view; the reversed Eight of Swords opens room to reassess the apparent limits; the reversed Nine of Swords asks whether that reassessment makes worry clearer or merely quieter. Together they suggest a discipline of conditional confidence. They do not tell us which market scenario will occur. More moderate inflation alongside sustained orders, project completion and cash generation would strengthen the constructive case. Persistent inflation, worsening demand indicators or evidence that spending is not producing usable returns would weaken it. The coming inflation report, technology results and Chinese trade release are opportunities to update, not guaranteed turning points.
For the coming week, choose one financial claim that is pulling you toward FOMO or panic. Before reading reactions, write its factual basis, the channel through which it might affect earnings or valuation, and one observation that would change your interpretation. Read the original release when available, then limit follow-up checks to a planned window. After the next relevant report, compare what changed in the evidence with what changed in your mood. If the practice only becomes a ritual for defending your first view, ask someone to challenge the weakest link. Success is a more honest update and a manageable attention habit, not a correctly guessed market move.
A question to take with you
Which assumption about growth, financing or valuation am I treating as settled, and what evidence would let me revise it without feeling that I have lost control?