The market mirror
AI earnings meet an energy squeeze: protecting clarity after the selloff
Falling yields offer relief, but AI earnings uncertainty and renewed oil supply risk keep the outlook fragile. A reading on security, regret and evidence before reaction.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · November 6, 2026 at 7:00 AM · New York
Associated Press via NBC Bay Area
AI-linked selloff sends S&P 500 down 4.4% ↗
Associated Press reports that Thursday’s S&P 500 fell 4.4% and the Nasdaq 5.5%, with concern about AI construction and borrowing costs. The 10-year Treasury yield declined from 4.90% to 4.84%. These are observed reactions. Lower yields can support valuations, yet a retreat into safer assets can coexist with weaker confidence in future profits. The selloff alone cannot tell us how much future disappointment prices now reflect.
Reuters via Investing.com
Qualcomm handset weakness weighs on shares ↗
Reuters reports that Qualcomm’s handset revenue fell 26% to $5.14 billion and its shares lost over 9% in early trading. Higher memory costs and weak handset demand complicated its diversification story. This is a concrete earnings issue: future data-center opportunities do not automatically replace present revenue or protect margins. One company’s product mix, however, cannot establish that every AI-related business faces the same demand problem.
Reuters via Yahoo Finance
Brent rebounds as tanker attacks renew supply concerns ↗
Reuters reports that Brent settled 3.88% higher at $98.29 after tanker attacks renewed supply concerns, reversing part of Wednesday’s sharp decline. More expensive fuel can squeeze household purchasing power and transport-intensive businesses, while benefiting some producers. A persistent supply disruption could also complicate inflation control. The price rebound is observed; the duration of the disruption and its eventual economic cost remain uncertain.
Freddie Mac release via GlobeNewswire/CompuServe
Mortgage rates decline for a third week ↗
Freddie Mac’s weekly survey put the 30-year mortgage average at 7.18%, down from 7.24% but above 6.22% a year earlier. The improvement offers limited relief to eligible borrowers; it does not establish a housing recovery. If lower financing costs persist, they could help transactions and related spending on furnishings and construction. The survey describes a particular borrower profile, so an individual household’s quote may differ.
Reuters via Investing.com
Bank of England lifts policy rate to 4% ↗
Reuters reports that the Bank of England raised its policy rate to 4%, citing energy-related inflation pressure; sterling and two-year gilt yields rose after the decision. That illustrates how supply-driven inflation can bring tighter financing even without uniformly stronger demand. The UK decision is relevant to multinational demand and global financing conditions, but it does not determine the Federal Reserve’s next move.
Federal Reserve
Fed held rates while flagging elevated inflation ↗
The Federal Reserve’s October 28 statement provides policy context: it held the target range at 3.75%–4%, described economic activity and productivity as strong, and said inflation remained elevated. Two members preferred a rate increase. That combination argues against assuming that an equity selloff guarantees easier policy. The statement does not establish current market expectations for the next meeting or how much policy risk equities have priced in.
A three-card reflection
01Backdrop
Four of Pentacles
Upright
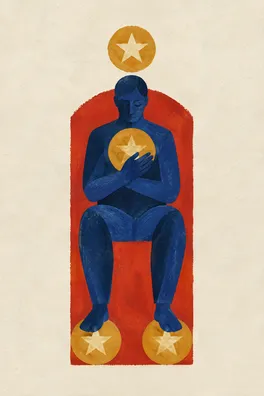
The upright Four of Pentacles places security and resource preservation in the backdrop. Its useful financial parallel is the difference between a business protecting its capacity to operate and a frightened investor demanding certainty. Today’s evidence gives reasons to scrutinize resilience: energy can absorb cash that would otherwise support consumption, and expensive financing can make investment projects harder to justify. These are economic channels, not messages established by the card.
My qualified view is that the setting remains fragile for valuations that require uninterrupted earnings growth, even though lower yields provide a counterweight. A valuation is the price investors pay for expected future profits; cheaper financing can make distant profits more valuable, but it cannot create missing customers. A company with dependable cash generation may therefore face a different problem from one relying on repeated outside financing. The evidence does not establish how much compensation current prices offer for either risk.
For a reader repeatedly checking losses, preservation can become a need to control every fluctuation. Begin by writing down the resources that support ordinary life: time, attention, essential spending and commitments. Then make one small adjustment to the information routine, such as replacing a stream of price alerts with a scheduled review. The blind spot is treating caution as complete analysis. Security also requires noticing evidence of resilience rather than collecting only threats.
02Pressure point
Five of Cups
Reversed
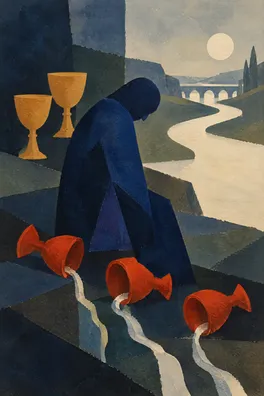
The reversed Five of Cups brings acceptance and recovery into the pressure point. In this position, it asks how disappointment changes the questions we ask. After a painful decline, an investor may search for a rebound merely to erase regret; after missing an earlier rally, the same person may feel pressure to catch the next one. Neither emotion establishes that expected earnings have improved. The reversal invites movement beyond loss without declaring that losses or economic pressures are finished.
Qualcomm’s report makes the distinction between a promising destination and a profitable transition tangible. New business can be real while existing revenue weakens. Equally, a slowing investment boom need not mean that all useful technology disappears. The pressure is to separate a change in the pace of spending from the eventual value of that spending. Stronger realized revenue, steadier margins and clearer project economics would strengthen a more constructive view; cancellations, weaker cash generation or persistent input-cost pressure would weaken it.
Try naming the loss you are trying to undo: money, confidence, status, or the feeling of having understood the story. If useful, ask someone you trust to review your reasoning rather than reassure you about an outcome. Write one fact that challenges your preferred interpretation. Acceptance becomes practical when it allows a new assessment without forcing either an optimistic recovery story or a permanent disaster story. The card offers a reflective possibility, never evidence of a market bottom.
03Grounded response
Queen of Swords
Upright
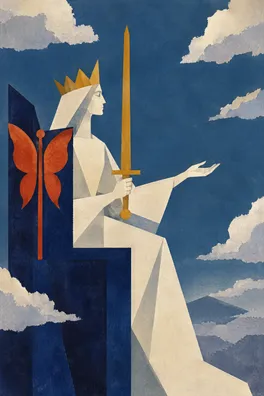
The upright Queen of Swords suggests independent discernment as the grounded response. Her clarity is especially useful when falling yields, rising oil and falling shares seem to demand one simple explanation. Those moves can reflect different forces. Lower financing costs may help some businesses while persistent energy costs hurt others, and a change in market sentiment can happen much faster than a change in a factory’s orders or a household’s income.
Use three short columns in a journal: verified fact, possible mechanism, and evidence still needed. For example, a reported mortgage-rate decline is a fact; improved housing demand is a possible consequence; sustained transaction activity would help assess that consequence. This keeps confirmation bias from turning a plausible link into an accomplished result. Apply the same standard to reassuring and alarming headlines, and check whether a market figure is an intraday observation or a completed session.
Give the review a boundary: one focused reading period followed by time away from the feed. Before reacting, state in one sentence what changed in the evidence and why it matters to your own time horizon and tolerance for uncertainty. If the answer is only that the headline felt urgent, allow more reflection. The Queen’s blind spot is severity: clear thinking need not become self-punishment, and asking for help can improve judgment. The purpose is a more accountable process, not perfect emotional control.
The three cards move from protecting resources, through releasing regret, toward stating a clear standard of evidence. Their reflective sequence fits a financial picture with opposing forces. Financing relief could support valuations and rate-sensitive activity, while uncertain AI earnings and energy supply risk could restrain profits and purchasing power. My present assessment is cautious about a rapid, broad improvement in fundamentals. It is also open to the possibility that sentiment has deteriorated faster than underlying business conditions. The verified snapshot cannot measure that gap or establish whether equities are now attractively valued.
A more supportive scenario would combine sustained easing in energy pressure with companies converting investment into revenue and cash, and financing relief reaching real activity. A less supportive scenario would combine prolonged supply problems, squeezed customers and disappointment in expected returns on AI spending. Strong productivity is a competing source of resilience highlighted in the reporting and Fed context: producing more from available resources can help growth without the same cost pressure. It does not remove the need to check demand, financing and company results separately.
For the coming week, choose one financial claim that triggers fear or excitement and keep the three-column journal for it. Before opening commentary, write what would change your mind. Review the claim at a planned time, noting whether you learned something new or simply encountered the same concern repeatedly. If the exercise becomes another form of compulsive monitoring, reduce its frequency; if a key fact was missing, improve the source rather than adding more opinions. Let the measure of success be clearer reasoning and a workable attention boundary, rather than whether a market move vindicates you.
A question to take with you
Which assumption about earnings, rates or recovery am I defending because changing it would make me feel regret, and what evidence would help me reconsider it?