The market mirror
An oil-led relief rally still needs an earnings bridge
Lower energy costs could ease pressure on households and profits. Slower orders, persistent inflation and financing needs make the next step conditional: distinguish a better mood from a stronger earnings outlook.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · November 5, 2026 at 7:00 AM · New York
Associated Press
US stocks rally as oil and Treasury yields fall after the midterms ↗
AP records a post-election stock rally alongside falling oil and Treasury yields. That is an observed repricing of hopes. My interpretation: sustained energy relief could improve consumer purchasing power and fuel users’ margins, while hurting producers’ revenue. A political result alone does not establish either outcome.
Reuters via Superhits 97.9
US services keep expanding while new orders cool and input prices stay high ↗
Reuters reports continued services expansion, slower new orders and still-high input prices. This combination suggests resilience with a cost squeeze, rather than a clean disinflation story. If firms cannot pass costs through without losing customers, margins could narrow; if they can, inflation could remain sticky and keep financing expensive. The report says the Fed held rates last week. That hold is not evidence of a coming cut.
U.S. Department of the Treasury
Treasury announces $125 billion refunding and keeps coupon auction sizes steady ↗
Treasury’s $125 billion refunding mostly replaces maturing debt; approximately $28 billion is new cash. Keeping coupon auction sizes steady avoids an announced increase in those sizes, but does not eliminate financing needs. Auction demand will help reveal the interest investors require. Higher yields would compete with equities and raise business financing costs; strong demand could limit that pressure. This source does not establish what dealers had priced in.
Palantir earnings release via SEC
Palantir reports strong revenue growth and raises its full-year outlook ↗
Palantir’s release shows rapid revenue growth and operating cash generation, alongside much slower growth in newly closed contract value. These measures cover different things and need not move together each quarter. The distinction makes future contract conversion and repeat demand worth examining. Management’s higher guidance is an expectation, not a completed result. This release alone cannot establish whether the shares are attractively valued or how much growth the price assumes.
Associated Press
Bank of England faces an expected rate increase after energy-driven inflation ↗
AP’s pre-decision report describes an expected Bank of England increase, not a completed one. The equity channel is conditional: tighter UK credit could weigh on housing, consumer demand and firms with refinancing needs, including international businesses exposed to those customers. Energy relief may help without immediately removing broader inflation pressure. No subsequent decision is assumed here.
A three-card reflection
01Backdrop
Six of Pentacles
Upright
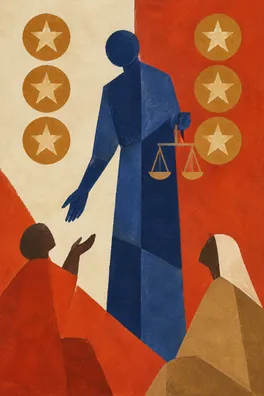
The Six of Pentacles upright brings the exchange of resources into the Backdrop position. Its concern is who can give, who needs support and what conditions accompany the transfer. As a reflective lens, it directs attention beneath an index’s movement: an improvement in the overall mood can distribute benefits unevenly. A household buying fuel, a transport company paying for it and an energy producer selling it do not experience the same price change in the same way. The card supplies the question about distribution; the reporting supplies the economic evidence.
My qualified view is that energy relief offers a plausible route toward broader economic support, provided it lasts. Less spending on essential fuel can leave more room for other purchases; lower operating costs can help businesses retain earnings or restrain selling prices. Neither adjustment is instant. Contracts, inventories, competition and a customer’s existing debts can delay or absorb the benefit. Meanwhile, a company whose selling price falls with oil may lose revenue before any other costs adjust. A broad rally therefore cannot substitute for examining who actually receives the relief.
For a reader feeling left behind by a rising market, the practical use of this card is to slow the comparison. Choose one business model or household budget you understand and trace where the money enters and leaves. Separate a lower cost from an actual improvement in cash available after obligations. The blind spot is assuming that assistance or cheaper inputs are freely available to everyone: access, timing and conditions matter. Ask what would need to change for the apparent benefit to reach the people or earnings you are thinking about.
02Pressure point
Five of Swords
Reversed
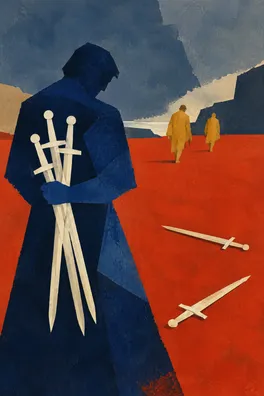
The Five of Swords reversed occupies the Pressure point. Its existing meaning allows a truce or withdrawal from an unproductive contest, while recognizing that consequences and resentment can remain. In this position it illuminates the temptation to treat a less threatening headline as a complete repair. It does not indicate a diplomatic outcome. A market can welcome the possibility of less conflict well before disrupted supply, expensive inventories or strained customer budgets have recovered.
The economic tension is between relief in expectations and the slower evidence in orders, costs and cash flow. The services report does not describe an economy that has stopped growing, yet its combination of softer new orders and elevated input prices leaves room for earnings disappointment. The strongest competing explanation is that demand remains resilient enough for businesses to absorb a temporary cost shock, especially if energy relief persists. That would make today’s caution too pessimistic. Alternatively, borrowing and essential expenses could continue to squeeze spending even after the initial market enthusiasm fades. Neither scenario is established by a single session.
This is where confirmation bias becomes costly to judgment. If you wanted the rally, you may skip the uncomfortable order data; if you expected trouble, you may dismiss genuine operating improvement as mere sentiment. Write one concrete harm that would need repair, such as a margin squeezed by costs, and one observation that would demonstrate repair. Avoid turning a discussion into a contest over who called the market first. The reversed card’s alternative reading is that withdrawal can leave an issue unresolved: taking a break from arguments helps only if you later return to the evidence you were avoiding.
03Grounded response
The Chariot
Upright
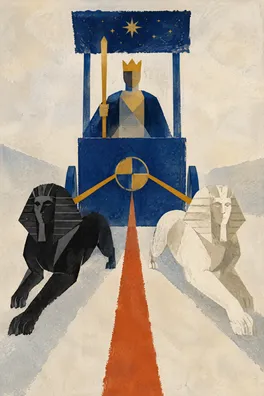
The Chariot upright brings opposing forces under a clear intention in the Grounded response position. Its determination is useful here because the evidence pulls in different directions: possible cost relief, ongoing expansion, persistent price pressure and substantial financing demands. Self-control means keeping those tensions visible while pursuing a defined understanding. It does not mean forcing them into one confident forecast or trying to outrun every price movement.
Define completion for your next information session before opening a feed. For example, finish when you can describe one channel from costs to earnings, identify the assumption that channel depends on and name the next relevant observation. Remove one unnecessary step, such as checking the same headline across five accounts. For a growth company, distinguish sales already recognized, cash actually collected and management’s future guidance. For a rate-sensitive business, ask when debt must be refinanced rather than assuming a daily bond move immediately changes all its interest expense.
Discipline can harden into rigidity. A neat plan can become overconfidence if it excludes information that changes the question. Keep a short place for disconfirming evidence and revise the research plan when facts warrant it. Treasury auction demand, subsequent company disclosures and the next official employment report can offer different windows on financing and demand; none alone resolves everything. The card’s challenge is to make purposeful progress without confusing the number of updates consumed with the quality of a decision process.
The three cards move from the distribution of relief, through the unfinished costs of conflict, toward a deliberate method of assessment. Their role is reflective. The financial judgment rests on the verified reports: a durable reduction in energy pressure could support real incomes and some margins, while softer orders, sticky costs and financing needs argue against treating a relief rally as proof of an economy-wide earnings acceleration.
The near-term change is in sentiment and market prices. The fundamental test takes longer: do input costs ease in company disclosures, do customers keep ordering, and does improvement turn into cash after financing expenses? The constructive case would strengthen if cost relief persisted alongside stable demand and credible cash generation. It would weaken if supply disruption returned, orders deteriorated further or debt funding became more expensive. A different risk is that strong demand sustains inflation and limits rate relief even while revenues grow. Higher sales and higher share valuations do not have to travel together: a valuation is the price paid for a stream of expected future profits, and the interest rate available elsewhere affects that price.
There is no complete measure here of market expectations or what is already priced into individual shares. The reported rally shows a response, but not how much future success is embedded in every valuation. Keep that unknown explicit rather than replacing it with a story about what everyone must believe.
For the coming week, try a two-minute journal after one scheduled news check each day. Record a verified fact, your proposed earnings or economic channel, and the evidence that could overturn it. Then name the emotion the headline triggered: FOMO, panic, vindication or frustration. Before any decision, return to your own time horizon and tolerance for loss; this reading supplies no transaction instruction. At week’s end, look for an assumption you revised and a repeated check that added no information. If the practice becomes another way to monitor prices compulsively, reduce its frequency and anchor it to new evidence rather than every market tick.
A question to take with you
Which part of my market view rests on an observed improvement, and which part rests on wanting relief to arrive?