The market mirror
Resilient demand, pressured margins: reading beyond the election reaction
Factory activity and hiring offer support for earnings, while Apple’s cost warning, unsettled oil supply and policy uncertainty complicate the valuation story. A reading on evidence, expectations and the urge to follow the crowd.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · November 4, 2026 at 7:00 AM · New York
Federal Reserve
Fed holds rates while inflation stays elevated ↗
The Federal Reserve’s October 28 statement kept its policy rate at 3.75%–4.00% and described inflation as elevated. Two dissenters wanted a quarter-point increase. This is the policy setting, rather than a new decision today. Continued inflation pressure could keep financing expensive for households and businesses. The statement offers no guarantee about the next decision; an unchanged rate does not itself establish that borrowing conditions will ease.
Reuters via KFGO
US factory activity strengthens amid costly inputs ↗
Reuters reported that October’s ISM manufacturing index rose to 55.5 from 54.5, with stronger production alongside still-widespread input inflation and supply constraints. An index above 50 indicates expansion across surveyed manufacturers; it is not a percentage growth rate. Demand can support suppliers’ revenue, yet shortages and higher costs can absorb that benefit before it becomes profit. AI-related equipment demand appears supportive, while other businesses may be more exposed to energy, tariffs and financing costs. Strong output and uncomfortable business sentiment can coexist.
Reuters via MarketScreener
September job openings and hiring rise as layoffs decline ↗
September job openings increased to 7.523 million, hiring rose and layoffs declined, according to Reuters’ account of JOLTS. Those levels support a picture of labor-market resilience, which could help household income and demand. They do not show an employment boom: the report also described a low-hiring, low-firing environment and noted weak survey participation. These are September observations, not a live reading of November. Later employment evidence will matter more than treating a single increase in vacancies as a settled trend.
Reuters via MarketScreener
Apple beats quarterly estimates but warns of margin pressure ↗
Apple exceeded quarterly revenue and earnings estimates, then forecast December-quarter gross margin of 45%–46%, down from 47.9% in the September quarter, citing memory costs and AI expenses. Gross margin is the share of sales left after the direct costs of supplying products and services. Reuters observed shares falling during the earnings call after initially changing little. That reaction belongs to that trading window. The fundamental issue is whether sales growth and pricing can offset higher costs; beating past estimates does not answer the forward profit question.
Reuters via Euronext
Dollar and Treasury yields retreat after Democratic congressional sweep ↗
Reuters reported Democratic control of both congressional chambers and a weaker dollar and lower Treasury yields as investors considered tighter AI scrutiny and its possible effects on growth. These were reported reactions and concerns, not enacted restrictions. Presidential veto power remains an obstacle to legislation. Lower yields could support equity valuations by reducing the rate used to translate future profits into today’s value, but that benefit may be offset if investment or earnings weaken. The available evidence does not establish how much of either possibility share prices already reflect.
Reuters via Yahoo Finance
Oil reverses lower as Iran-war uncertainty persists ↗
The updated Reuters oil report described prices turning lower after rising earlier, with military strikes and mediation continuing and the sides still far from an agreement. Petroleum flows from the Middle East remained below pre-war levels, and limited refined-product exports could delay relief at the pump. Sustained cheaper fuel could help transport costs and household purchasing power; renewed disruption could reverse that benefit. A volatile futures session alone cannot establish that companies’ delivered energy costs, or consumers’ fuel bills, have fallen.
A three-card reflection
01Backdrop
Three of Cups
Reversed
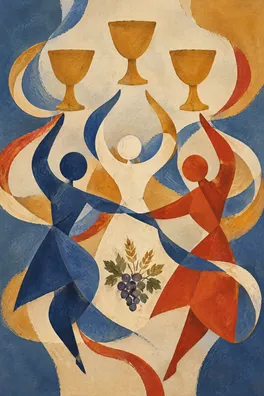
The Three of Cups reversed, in Backdrop, brings attention to a gathering that has lost its balance: gossip, exclusion or a search for approval can turn company into a drain. Applied reflectively to this market setting, it asks how a shared story becomes more persuasive than the evidence underneath it. The manufacturing and labor reports provide reasons to take demand seriously. Apple’s warning shows why strong activity can still fail to protect margins. Neither fact disappears because a group finds one narrative more emotionally satisfying.
An investor conversation might celebrate lower yields as an automatic invitation to optimism, or interpret every discussion of AI regulation as proof that growth is finished. Both shortcuts erase a causal link. Lower yields can make future profits more valuable today, but slower investment could reduce those profits. A weaker dollar can lift translated overseas revenue for some US companies while raising imported input costs for others. These are conditional channels, not demonstrated outcomes for every business. We do not know the full set of expectations embedded in prices.
Notice whether fear of missing out makes disagreement feel like exclusion from the group. Before accepting a confident claim, write the reported fact, the proposed economic link and the remaining assumption on separate lines. Choose one person who can challenge the link without turning the exchange into a contest. The reversed card need not mean every community is unreliable; it may mean the way you participate has become exhausting. Stepping out of a repetitive commentary thread can leave more room for useful companionship and careful judgment.
02Pressure point
Two of Cups
Upright
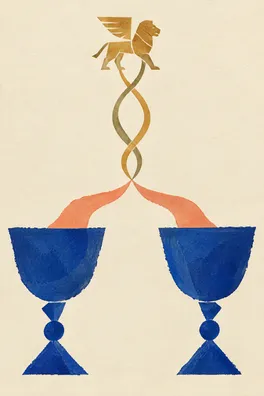
The Two of Cups upright places reciprocity and an equal relationship at the Pressure point. Its symbolism is about the connection between two people; here it offers a metaphor for checking whether the two sides of an investment argument actually meet. Healthy demand and durable profitability are related, but they are not interchangeable. Apple’s outlook makes that distinction concrete: sales can impress while the cost of producing and supporting them leaves less room for profit.
There is also a relationship between earnings and the price paid for them. An attractive growth story does not by itself tell us whether its valuation is justified, just as a cheaper-looking price does not establish that expected earnings are secure. The election reaction adds another tension: lower rates may support valuations while concern over future AI investment weighs on earnings expectations. A plausible concern is not yet a law, and a law would still need to be assessed for its actual scope and timing. The evidence supports watching both sides rather than assuming they have already reconciled.
Use the card’s conversational action literally with a trusted discussion partner: state the claim you are trying to understand, then reflect back their reasoning before defending yours. Ask what has actually been reported and what you are each hoping will follow. Confirmation bias can make agreement feel like verification, especially when both people rely on the same headline. If you cannot yet identify the cost, demand or policy evidence that would change your view, the conversation may be supplying reassurance rather than a balanced examination. Mutual respect leaves room to remain uncertain.
03Grounded response
Ten of Wands
Reversed
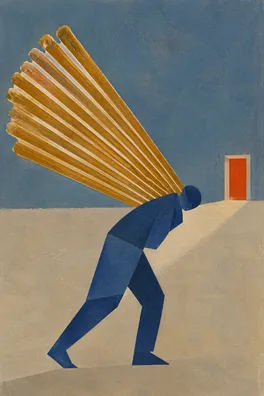
The Ten of Wands reversed, in Grounded response, has two possible directions: a burden can grow because it is never shared, or relief can begin when excess responsibility is put down. In an information-heavy market, the burden may be the belief that responsible attention means continuously monitoring every political statement, oil tick and technology opinion. Carrying all of it does not make the underlying uncertainty disappear.
A manageable response is to narrow the job. At a chosen review time, examine one demand indicator, one cost or margin indicator and one policy development relevant to the question you are studying. Keep their dates visible. September labor data and a November market reaction answer different questions, so do not let their proximity on a screen make them equally current. When you feel panic or urgency, record the trigger before opening another source. Repeated versions of the same story add emotional weight without necessarily adding evidence.
The other side of this reversed card is avoidance disguised as relief. Limiting information should still leave room to review real obligations, your time horizon and the uncertainty you can tolerate. Share a question with a qualified person when it exceeds your knowledge; do not outsource judgment to the loudest voice. For this week, remove one redundant alert and replace it with a scheduled check of an original report. Afterwards, notice whether you can explain the issue more clearly, and whether the urge to react has changed. The aim is a sustainable process, not the impossible task of having no feelings about risk.
My qualified view is that the evidence remains more supportive of continued economic activity than of an abrupt demand collapse, while the case for a broad improvement in corporate profitability is less secure. Factory expansion and labor resilience provide support for revenue. Component shortages, energy disruption and expensive financing can keep that revenue from flowing fully into earnings. This is a mixed fundamental setting, even when a political headline produces a sharp moment of relief or alarm.
The short-term election response should therefore be read separately from the slower business adjustment. Lower Treasury yields could ease valuation pressure, and possible limits on AI spending could reduce some supply bottlenecks. The competing possibility is that the same slowdown weakens orders for businesses supplying that investment. Neither the net earnings effect nor how fully it is priced in is established here. Similarly, oil moving lower becomes more economically helpful if physical supply and refined-product exports improve; a trading reversal without that follow-through is weaker evidence.
The constructive part of this view would strengthen if subsequent employment reports show resilient incomes and hiring, companies maintain orders while protecting margins, and energy relief reaches actual delivered costs. It would weaken if layoffs rise, orders soften or cost pressure persists while revenue slows. Enacted policy, rather than speculation about its direction, would help clarify the AI question. None of these conditions supplies a mechanical market forecast or an instruction to transact.
The cards trace a practical movement from the drain of group approval, through an honest exchange, toward a lighter and more accountable information routine. For the coming week, choose one market belief and keep a small record with three entries: what the source says, how you think it reaches earnings or valuations, and what evidence would change your mind. Review it at two planned times rather than after each price notification. If the record grows but your explanation does not improve, reduce duplication; if you discover a relevant missing fact, adjust the question. The experiment succeeds when you can name both your reasoning and your emotional trigger with greater accuracy.
A question to take with you
Which market story makes me feel that I must join the crowd immediately, and what unverified link between the headline, future profits and today’s price am I treating as certain?