The market mirror
An AI rebound meets the cost of capital: earnings, oil and patient judgment
Earnings offer support, but borrowing costs and energy disruption still test the rebound. A reflective reading on distinguishing relief from durable improvement and resisting the urge to chase certainty.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 27, 2026 at 7:00 AM · New York
Associated Press
AI shares lead Monday’s Wall Street rebound ↗
AP reports Monday’s S&P 500 gain of 0.7% and a ten-year Treasury yield of 4.98%, slightly below late Friday. That is an observed rebound, rather than proof that the earnings outlook improved. Major technology results were still ahead. My interpretation is that a lower long-term yield can ease valuation pressure: investors discount future profits less heavily when the alternative return on bonds falls. But this small move does not establish a lasting change in financing conditions. A rally can reflect renewed appetite for risk before the underlying cash flows are known.
Associated Press
Fed pause expected, with inflation still unresolved ↗
AP’s Fed preview says an October pause was widely expected before Wednesday’s decision. That expectation is not a decision already taken, and a pause would not itself be a rate cut. The distinction matters for households financing purchases and businesses refinancing debt. An unchanged policy rate can reduce immediate uncertainty while leaving borrowing expensive. Because a pause was already anticipated, its announcement alone might provide little new support; the explanation and future policy signals could matter more. The reporting does not establish how much of any later policy path is embedded in every asset price.
Reuters via Business Recorder
Oil retreats as diplomacy competes with supply threats ↗
Reuters reports Monday’s intraday oil retreat alongside mediation efforts, while continuing threats to Saudi supply and shipping kept the relief fragile. These are a price observation and unresolved physical risks, not confirmation of restored supply. If lower energy prices persist because supply becomes safer, freight costs and household fuel bills could ease, supporting margins and spending elsewhere. If prices instead fall because demand is weakening, the earnings implication is less favorable. Energy producers and energy-consuming businesses can face opposite effects; one headline cannot describe the whole equity market.
US Bureau of Labor Statistics
September inflation provides the policy backdrop ↗
The BLS release of October 14 showed September CPI up 0.6% monthly and 3.7% annually, with gasoline responsible for over half the monthly increase. This is the older inflation backdrop, not a new October reading. Energy explains much of that month’s acceleration, but core prices also rose 0.3%. The financial question is whether cost pressure fades or spreads into other prices. Persistent pressure could restrict the Fed’s room to ease and squeeze purchasing power; a durable decline without weaker employment or demand would be a more supportive combination.
General Motors investor relations
GM cash flow improves as profit guidance narrows ↗
GM’s October 20 release narrowed adjusted operating-profit guidance without changing its midpoint, while raising its adjusted automotive free-cash-flow range. These are distinct changes, and the company’s guidance remains conditional. The cash-flow improvement is supportive evidence from a business outside the AI theme, but one manufacturer cannot stand in for the economy. Cash generation means more flexibility to finance operations and investment. A narrower profit range alone is not a broad earnings upgrade, and per-share gains can also reflect a changing share count rather than stronger demand.
Associated Press
Canada and Ontario announce support amid trade friction ↗
AP’s October 21 report describes announced Canadian and Ontario industry support amid continuing trade friction, with no indicated negotiating breakthrough. It provides context for supply chains rather than news of a new trade settlement. Public support may cushion investment and employment where tariffs raise costs, but it does not remove the trade barrier. For integrated manufacturers, disrupted sourcing can affect margins, delivery times and expansion plans on both sides of a border. Announced support and actual spending also occur on different timetables.
A three-card reflection
01Backdrop
Five of Swords
Reversed
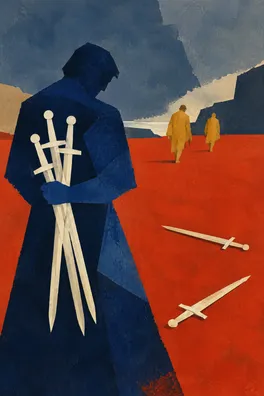
The reversed Five of Swords, in Backdrop, turns attention from winning a contest toward the costs that remain after it. Its supplied meaning allows for a truce or reconciliation while resentment and consequences linger. As a reflective lens on this market setting, it asks whether relief from a confrontation has been mistaken for repair of the damage. The card supplies no evidence that a diplomatic truce exists; the oil report describes efforts and continuing risk.
My qualified view is that this rebound has some fundamental support, but the evidence does not yet justify treating financing and energy pressures as resolved. GM’s cash-flow outlook offers a concrete counterweight to a story of universal deterioration. At the same time, lower oil on one day does not immediately restore shipping reliability or reverse the costs already absorbed by businesses and families. That gap between a change in mood and a change in operating conditions is the central backdrop.
Imagine reading a hopeful diplomacy headline immediately after a volatile week. Relief may help you think more clearly, yet it can also become FOMO if you assume everyone else knows a recovery is secure. Write down the specific cost channel you believe has improved: fuel, freight, interest expense or customer demand. Then identify what remains unverified. An alternative reading is that you have stayed attached to a pessimistic argument and dismiss every improvement; leaving an unwinnable debate can mean allowing favorable evidence into your journal too.
02Pressure point
King of Wands
Reversed
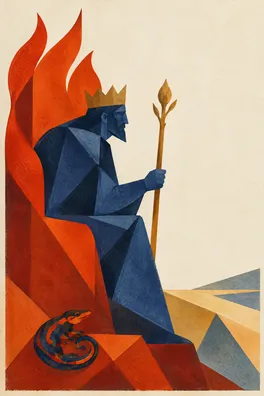
The reversed King of Wands occupies Pressure point. Its meaning concerns impulsive leadership, unrealistic promises and weak follow-through. Here the symbolic tension is between a persuasive growth story and the resources required to deliver it. This is not a judgment about any executive’s character. It is an invitation to examine claims by the same standard whether the speaker excites or irritates you.
AI construction can generate real orders for suppliers and work for the wider economy before its ultimate users earn adequate returns. Those two facts can coexist. If projects require costly funding, stronger revenue may still leave less cash after investment and interest. A valuation is the price investors place on a stream of future earnings; even a successful business can face a demanding price if expectations outrun delivery. The reporting does not tell us exactly what future profit path the market has priced in, so a confident verdict that shares are cheap or expensive would exceed this evidence.
The practical pressure is overconfidence disguised as conviction. Before consuming another enthusiastic forecast, choose one delivery question: are customers paying for the service, are margins holding up, or is cash generation keeping pace with spending? Upcoming results can inform those questions without settling them forever. Also allow the competing case: front-loaded investment can be rational when later demand is strong. Avoid treating every large budget as waste, just as you avoid treating ambition as earned profit. The useful response to a bottleneck is to name it clearly, not demand that a favorite narrative prove itself through tomorrow’s price.
03Grounded response
Seven of Wands
Upright
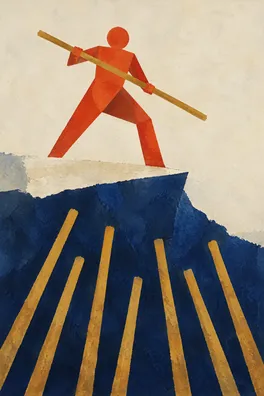
The upright Seven of Wands, in Grounded response, represents courage and defending something valuable under pressure. In this position, what deserves defense is your method of judgment and your capacity to revise it. Holding your ground does not require holding an opinion unchanged. The card’s boundary can protect attention while evidence develops.
The financial discipline is to separate three questions: what happened, how it might affect cash flows, and how much of that effect prices already reflect. For example, an expected Fed pause belongs in the first column only after it happens; its consequences remain conditional, and its pricing impact may already be partly anticipated. A sustained easing in energy and financing costs alongside resilient demand would strengthen the supportive case. Renewed supply disruption, weaker company cash generation or more persistent inflation would weaken it. Lower yields caused by a worsening growth outlook would also call for a different interpretation than lower yields caused by easing inflation.
Set one manageable information boundary for the coming week: a planned window to read original releases, followed by a pause before interpreting price alerts. Offer yourself a practical alternative to repeated checking, such as recording one piece of evidence against your current view. If a move triggers panic or a wish to recover a recent loss, name the feeling before analyzing the news. The blind spot is defensive stubbornness: if your boundary prevents relevant new information from entering, it has become a wall. Protect a repeatable process that fits your own time horizon and tolerance for uncertainty, while leaving room for revision.
Together, the cards move from the aftermath of conflict, through the temptation of forceful promises, toward a boundary that preserves judgment. The economic view underneath that symbolism is cautiously supported by pockets of cash generation and the possibility of cost relief, but constrained by unresolved energy disruption and expensive financing. This is a conditional assessment of the evidence, not a forecast from the spread or an instruction to transact.
Near-term sentiment may improve when oil falls or the Fed avoids a surprise. Fundamentals need a longer test: sustained customer demand, earnings that convert into cash, and investment that can be financed without eroding the benefit it creates. One alternative is that high spending is laying the groundwork for durable productivity gains. Another is that today’s supplier revenue masks tomorrow’s weaker returns for the businesses paying the bills. The forthcoming earnings explanations and subsequent inflation data can help distinguish them; this snapshot cannot assign probabilities or establish the full set of market expectations.
For a one-week experiment, select one economic claim you feel strongly about. At the first reading session, write the verified fact, your proposed transmission channel and the evidence that would change your mind in separate sentences. At each later session, add only genuinely new information. Notice whether the urge to check prices rises when you have no new evidence: that may reveal anxiety or FOMO rather than a research need.
At week’s end, assess the experiment by whether your reasoning became clearer and more revisable, rather than whether one market move agreed with you. If the practice feels burdensome, follow one channel instead of many; if important information was missed, adjust the reading window. The reversed cards make room to leave the contest of being right, while the Seven of Wands asks you to defend the care with which you decide what you believe.
A question to take with you
Which part of my market view rests on a verified change in earnings or costs, which part rests on hoped-for relief, and what evidence would let me revise it without feeling defeated?