The market mirror
Strong demand, expensive growth: weighing earnings against energy and rates
Oil relief offers a brighter morning, while costs and borrowing rates still test profits. Justice asks for consistent evidence before optimism or fear becomes conviction.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 26, 2026 at 7:00 AM · New York
Reuters via Euronext
Oil eases as markets face a week of policy and earnings tests ↗
Reuters reported a modest rise in European shares and US index futures as oil eased following reports of mediation in Tehran. Those are observed early-session reactions, not a US closing result or proof of a lasting supply improvement. Cheaper energy, if sustained, could ease transport and production costs and leave households more spending room. Reports of fresh attacks remained unconfirmed by Saudi authorities, so relief in sentiment still rested on an unsettled situation.
S&P Global
US business survey shows strong expansion and rising price pressure ↗
S&P Global’s October flash survey showed continued strong business expansion alongside faster selling-price increases. That combination can support sales while complicating inflation control. A business survey is an early signal, not measured GDP or a completed earnings season. The key question is whether demand remains strong after customers absorb higher prices, rather than whether a single activity reading looks reassuring.
University of Michigan
Consumer sentiment stays weak as affordability weighs on major purchases ↗
The University of Michigan reported sentiment at 48.0, almost unchanged from September, with durable-goods buying conditions down 18%. Higher rates and affordability were central concerns. This describes attitudes rather than actual spending: it flags vulnerability in financed purchases without establishing that consumption has already contracted. Different experiences among households with large and small stock holdings also caution against treating the stock market as a complete picture of household resilience.
Procter & Gamble
P&G sales grow while costs limit earnings growth ↗
P&G reported sales growth of 4% and core earnings-per-share growth of 1%, while core gross margin fell 150 basis points, or 1.5 percentage points. Its forecast commodity headwind is management guidance, not an expense already realized for the full year. The result illustrates why stronger revenue need not produce equally strong profit growth. One global staples company cannot establish the outcome for all sectors, but its cost bridge is more informative than a sales headline alone.
Reuters via Kitco
US reshapes Canadian tariffs with selective exemptions and additions ↗
Reuters reported selective removal of 50% tariffs on Canadian products from October 30, alongside additions to the tariff list. Affected importers could receive cost relief, while newly covered businesses face the opposite pressure. The aggregate economic benefit remains unclear without the value and composition of both sets of goods. Calling the change a broad trade thaw would go beyond the evidence.
Federal Reserve
September Fed increase provides context for the coming decision ↗
The September Federal Reserve statement raised the policy-rate range to 3.75%–4.00%. It is background for this week’s decision, not fresh October action. Higher borrowing costs can slow housing, financed purchases and business investment, while higher bond yields can reduce the value investors assign to future profits. Reuters’ Monday report described expectations for an October pause; an expected pause would not itself establish cheaper credit or an end to inflation risk.
A three-card reflection
01Backdrop
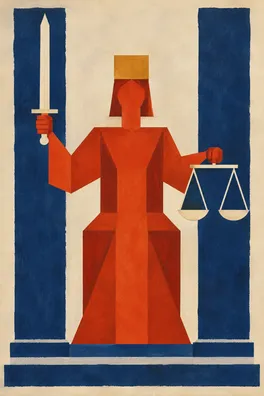
Justice
Upright
Justice upright places facts, responsibility and cause and effect in the Backdrop. As a reflective lens, it asks us to weigh the economy with the same standard on encouraging and troubling days. The current evidence supports a cautious distinction: business demand looks resilient, while the cost of delivering that growth remains a concern. Neither a weak household mood nor a strong business survey can carry the entire conclusion. Their different subjects and time horizons matter.
For equities, earnings and valuations are separate parts of the balance. Earnings are the profits companies generate; a valuation is the price investors are willing to pay for those profits. Revenue can grow while higher inputs absorb the benefit. Even expanding profits may not lift share prices if borrowing rates rise or investors become less willing to pay for distant earnings. Conversely, easing costs could improve the profit outlook without a dramatic acceleration in sales. These are conditional channels, not moves established by today’s headlines.
Justice’s practical invitation is to add a relevant fact and consider another explanation. When a headline confirms your view, write the strongest competing account beside it. A positive survey could reflect enduring demand, or some orders could be brought forward to avoid future disruption. A subdued consumer reading could foreshadow restraint, or households could keep spending despite frustration. The blind spot is mistaking a balanced assessment for equal weight on every claim: give stronger, more direct evidence more influence, and leave unresolved questions unresolved.
02Pressure point
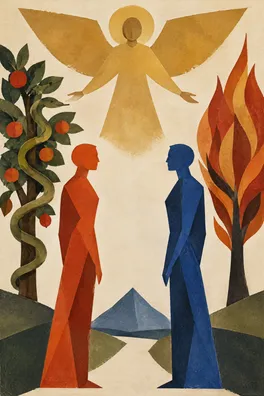
The Lovers
Reversed
The Lovers reversed brings discord and conflicting commitments to the Pressure point. Here the tension is between attraction to growth and the conditions needed to sustain it. It is possible to admire a company’s opportunity while questioning how much cash, financing and patience it requires. It is also possible for aggregate activity to remain firm while households exposed to high rates feel squeezed. The card does not prove a market imbalance; its meaning helps us stay with conflicting evidence without forcing premature harmony.
My qualified view is that the evidence is more consistent with resilient but costly expansion than with either effortless growth or an established broad collapse. That leaves equities sensitive to whether revenue becomes cash and whether inflation keeps financing expensive. Businesses able to protect margins without exhausting customer demand may cope differently from those with weak pricing power, heavy energy use or near-term refinancing needs. These are business characteristics to examine, not a ranking of sectors or an instruction to act.
The emotional pressure can be FOMO when a relief rally appears to leave you behind, followed by panic when the next oil headline reverses the mood. Name one essential need in your own decision process, such as understanding the downside within your time horizon, and one negotiable preference, such as getting an explanation immediately. Avoid borrowing certainty from a confident commentator just to end the discomfort. The alternative reading is that apparent contradiction reflects uneven timing: profits, household budgets and policy respond at different speeds. Ask what evidence would connect them before declaring that one side must be wrong.
03Grounded response
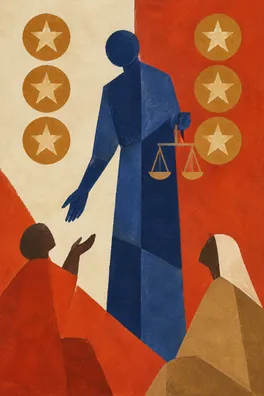
Six of Pentacles
Reversed
The Six of Pentacles reversed puts unequal exchange and help with conditions in the Grounded response. Its reflective question is who receives a benefit, who pays for it and what obligations travel with it. Selective tariff relief illustrates why the scope of an announcement matters. Likewise, lower energy prices may help an importer while changing a producer’s revenues, and easier funding for one business does not establish easy credit for everyone. The symbolism prompts investigation; the reporting supplies the facts.
Apply that question to information as well. A stream of free opinions may cost attention and encourage dependence on someone else’s confidence. Before adding another alert, identify what decision-relevant gap it would fill. If repeated price checks only intensify urgency, set two brief news windows and use the time between them to read a release or reconcile a cost estimate. This is a boundary around information intake, not a reason to ignore material developments.
Make an uneven exchange specific: are you giving an hour of attention to commentary that offers no verifiable evidence, or treating reassurance as analysis? Record the claim, its source and what remains unknown. Do not infer that assistance is manipulative merely because this card is reversed; useful guidance can be both generous and limited. The aim is to retain the freedom to say that a source has helped enough, and to return to your own time horizon, constraints and risk tolerance before making any consequential decision.
Justice asks for consistent standards, The Lovers reversed holds conflicting evidence apart long enough to understand it, and the Six of Pentacles reversed examines how costs and benefits are distributed. Together they offer a discipline for this economic setting: follow the path from demand to revenue, from revenue to margins, and from profits to the financing conditions that shape their value. None of the cards establishes what markets will do.
The financial view remains cautiously concerned about the cost side of resilient growth. A lasting reduction in energy and supply pressure, company reports showing healthy cash generation, and inflation evidence that permits less restrictive financing would strengthen the case that expansion can translate into durable earnings. Renewed disruption, shrinking margins despite sales growth, or weaker actual household spending would weaken it. An alternative is that productivity and cost savings offset more pressure than expected. That possibility deserves examination alongside the risks.
Near-term relief can arrive before those fundamentals improve. Reuters described market expectations for a Fed pause, but this snapshot does not tell us how much of every earnings outcome, tariff change or geopolitical scenario is already reflected in prices. An event being favorable in economic terms does not guarantee a favorable market reaction. Compare reported outcomes with documented expectations when available; otherwise mark the comparison unknown.
For the coming week, keep a short journal with three entries for one important story: verified fact, your causal interpretation, and evidence that would change it. Add the feeling it triggers and whether another check would provide information or only temporary reassurance. Revisit the entry after a company report or policy release, without turning it into a scorecard for daily prices. Adjust the experiment if your chosen sources miss meaningful developments, but keep the pause between new information and commitment. Which assumption are you most tempted to protect because changing it would feel like admitting a mistake?
A question to take with you
When a headline produces urgency, what evidence would genuinely change your view, and what are you seeking mainly to calm the feeling?