The market mirror
AI’s cash test, oil’s cost shock: planning beyond the selloff
Strong sales do not settle the question of investment returns. Today’s reading weighs AI financing, energy costs and resilient employment, then explores how to question a market story without letting fear take over.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 23, 2026 at 7:00 AM · New York
Reuters via Moneycontrol
Meta raises the floor of AI spending guidance and plans a new share class ↗
Reuters reports that Meta’s quarterly revenue exceeded the LSEG estimate and its fourth-quarter revenue forecast also exceeded estimates. At the same time, the company raised the floor of its annual capital expenditure range to $135 billion, retaining the $145 billion ceiling, and announced a new non-voting share class to support financing. Revenue growth and the cost of producing future growth are separate questions. Capital expenditure pays for assets that can serve customers over time; it uses cash before the full return is known. My interpretation is that demand evidence remains supportive, but the path from sales to cash available for shareholders needs closer examination. New shares could broaden financing options and, if issued, dilute existing ownership. The announcement alone does not establish how much dilution will occur or whether the investment will earn an adequate return.
Reuters via Metrobank Wealth Insights
Oil rises as attacks increase concerns about Gulf supply ↗
Reuters links Thursday’s oil rally to further attacks on Saudi targets and concern about Gulf supply. Brent futures were $111.64 at 06:26 GMT, an intraday observation rather than the closing price. The report also cites a weekly decline in US crude inventories. These facts identify a supply risk; they do not establish the duration of disruption. If higher energy prices persist, transport and production costs could squeeze businesses unable to pass them on. Passing costs to customers can protect margins while reducing household spending power and demand elsewhere. Oil producers may receive higher selling prices, but operational exposure and costs matter too. This is a conditional earnings and inflation channel, not a claim that every energy company benefits or that a new policy-rate increase is certain.
U.S. Department of Labor
New jobless claims fall while continuing insured unemployment rises ↗
The Labor Department reports initial unemployment claims of 194,000 for the week ending October 17, down from a revised 200,000. Continuing insured unemployment rose to 1,728,000 in the separate week ending October 10. These measures cover different weeks and populations; they should not be added together or treated as the whole labor market. Low new claims are a counterweight to an immediate broad-collapse narrative: fewer new layoffs can help preserve wage income and consumer revenues. Rising continuing claims temper that reassurance because people already receiving benefits may face a different experience. Neither series alone settles hiring strength, household purchasing power or the direction of the Fed. I would look for persistent changes across labor and spending evidence before converting one weekly print into a macroeconomic conclusion.
Reuters via MarketScreener
Treasury yields fall sharply despite an oil price jump ↗
Reuters’ later session commentary records Treasury yields falling by as much as 20 basis points across the curve while Brent climbed above $112. A basis point is one hundredth of a percentage point. It also reports a 2.6% Nasdaq decline and a 6.7% semiconductor-index decline. These are observed reactions during Thursday’s session, not Friday’s forecast. Lower government-bond yields can reduce the discount rate used to value future company cash flows and eventually ease some financing costs. Yet a safety-driven bond rally can accompany weaker confidence in growth. Companies’ borrowing costs also depend on the extra compensation lenders demand for their own credit risk. The simultaneous equity decline therefore does not prove that cheaper financing has arrived for all businesses, or that the Fed has changed course.
Reuters via MarketScreener
Kering and Holcim results produce sharply different European reactions ↗
Reuters’ early European report offers a useful contrast within earnings: Kering fell 10.4% after Gucci’s quarterly sales declined, while Holcim gained 5.2% after stronger-than-expected sales and profit and a raised annual earnings forecast. Those figures refer to the early session, not its eventual close. The contrast argues for examining business evidence beneath the common risk mood. Weak sales at one luxury brand are not a complete measure of global consumer demand; stronger results at one cement company are not proof of a construction boom. For equities, the useful questions concern each business’s volumes, pricing, costs and ability to turn revenue into profit. This snapshot does not tell us how much good or bad news was already embedded in either valuation.
A three-card reflection
01Backdrop
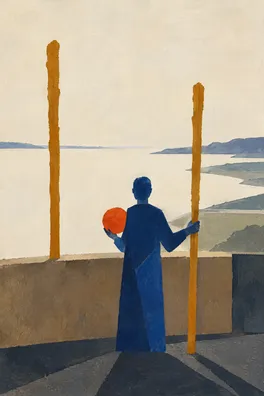
Two of Wands
Upright
The upright Two of Wands brings planning on an existing foundation to the Backdrop position. Its emphasis is a choice about expansion, rather than expansion already accomplished. That distinction fits today’s economic question: large investment commitments and strong revenue evidence can coexist with uncertainty about the cash returns still to come. The reporting supplies the facts; this card supplies a way to examine our response to them.
My qualified view is that the combination of AI financing demands and renewed energy supply risk makes the broad equity outlook more fragile, even though low new claims argue against assuming an immediate collapse in household demand. The channels differ. AI spending can support suppliers and productive capacity now while postponing cash returns for the spender. Persistent oil costs can erode margins or purchasing power across the wider economy. Neither effect should be compressed into the single label “good growth” or “bad market.”
Imagine feeling that every possible direction must be chosen before the next opening bell. The card’s wider horizon suggests writing two plausible paths: investment earns useful returns while energy disruption eases; or cash needs remain high while costs spread into demand. For each, name a benefit, a cost and one fact still needing verification. This is a research exercise, not a portfolio instruction. The blind spot is using elaborate scenarios to avoid admitting that current valuations and embedded expectations are unknown. A useful plan makes those gaps visible and identifies which evidence is worth waiting for.
02Pressure point
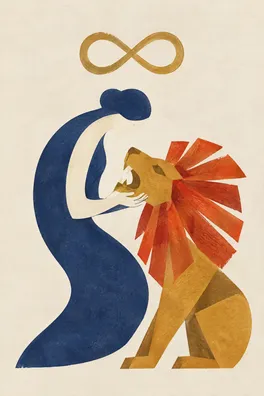
Strength
Reversed
Strength reversed occupies the Pressure point. Its supplied meaning includes wavering confidence, emotional impulses and the temptation to conceal insecurity through toughness. Here it reflects the strain of trying to sound certain when growth, funding and inflation signals pull in different directions. It does not say that a company, an investor or the economy is weak. It asks how uncertainty changes the way we handle evidence.
A revenue beat can trigger fear of missing out; a sharp sector decline can turn that same person toward panic. Both reactions can skip the financial question. Sales above an estimate do not by themselves establish an attractive valuation, while a falling share price does not by itself establish deteriorating long-term demand. Equally, the comforting thought that lower Treasury yields will rescue every valuation ignores the possibility of weaker expected cash flows or more expensive company credit. The pressure is to turn one observable fact into an answer to every question.
Try noticing the moment a headline becomes a verdict about your own competence: “I missed it,” or “I should have known.” Name the limit underneath it, such as insufficient time to read a release or uncertainty about financing terms. Ask a trusted person to challenge one causal link in your reasoning, without asking them to make a financial decision for you. Reversed Strength can also point to excessive self-restraint: suppressing all concern is no more informative than reacting to every alert. A short pause is useful when it restores the ability to distinguish a fact, an assumption and an emotion.
03Grounded response
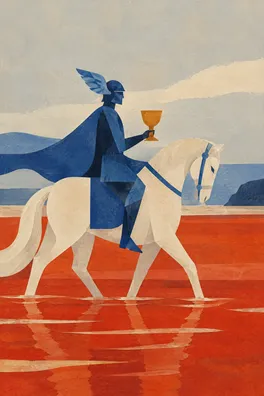
Knight of Cups
Upright
The upright Knight of Cups makes the Grounded response relational and deliberate. His meaning is feeling expressed through a considerate invitation or imaginative action. In this position, the invitation can be a low-pressure conversation about what a market story means to you. The aim is to give concern a useful form, while respecting both your own limits and another person’s willingness to participate.
For example, invite a trusted reading partner to review a short journal entry: “Could we spend fifteen minutes checking where my interpretation goes beyond the sources?” Put the verified event in one column, your proposed earnings or valuation channel in another, and the missing evidence in a third. If you find that you are collecting only AI optimism or only oil-related alarm, deliberately read the strongest relevant counterargument once. Repeatedly refreshing the same price does not add another independent piece of evidence.
The Knight’s idealism has a blind spot: an appealing story can feel true because it expresses a hope or fear elegantly. Keep the warmth of the conversation, then ask what would disconfirm the story. Improving cash generation alongside investment would strengthen the more constructive AI case; continued funding strain without clearer returns would weaken it. Sustained relief in supply and energy costs would ease the margin concern; persistent disruption and weaker demand would deepen it. These are conditional checks, not predictions drawn from the card.
Today’s financial judgment is cautious about the combination of future cash demands and current cost pressure, with employment providing an important counterweight. The strongest competing explanation is that productive investment and still-resilient income can sustain business growth while energy disruption proves temporary. The evidence does not settle that contest, and the snapshot provides no reliable measure of how fully either path is priced into the broad market. A forceful selloff demonstrates changed willingness to bear risk; it does not calculate fair value.
The cards trace a reflective sequence: the Two of Wands compares directions, reversed Strength notices the urge to force certainty, and the Knight of Cups turns that discomfort into a thoughtful exchange. This sequence is useful precisely because it does not supply a market forecast. It helps separate the short-term emotional force of prices from the slower work of examining revenue, margins, capital requirements and financing.
For the coming week, choose one daily reading window and one question to follow, rather than trying to monitor everything. Start with a three-line record: what happened, how it might reach company cash flows, and what would change your interpretation. Before adding a fresh article, ask whether it contributes new evidence or repeats an existing event. At week’s end, review whether your view changed because the evidence changed or because the language became more frightening or exciting. If the practice encourages compulsive checking, shorten the window and reduce the number of stories.
Use the review to reconnect the news with your own time horizon and capacity for uncertainty, without forcing an immediate transaction. Planning remains useful when the eventual answer is “I need more evidence.” What assumption becomes harder to defend when you explain its path from headline to earnings in plain words?
A question to take with you
When a market move makes me want immediate certainty, which part of my view is verified, which part is an assumption, and what evidence would genuinely change my mind?