The market mirror
Strong production, costly capital: testing the foundations beneath equities
Chip profits and industrial growth offer support, but inflation, energy disruption and financing costs demand a closer look at earnings quality—and at the urge to react.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 19, 2026 at 7:00 AM · New York
Reuters via Investing.com
US inflation accelerates in September ↗
Reuters reports that September consumer prices rose 0.6% from August and 3.7% from a year earlier. The monthly gain matched its economist poll; the annual reading exceeded it. This is a constraint on easy monetary relief, rather than proof of the next Fed decision. Persistent price increases can squeeze household purchasing power and business margins; efforts to contain them can keep financing expensive. The balance depends on wages, pricing power and demand, which this release alone cannot settle.
Federal Reserve
US industrial output rises, led partly by utilities ↗
The Federal Reserve reports September industrial production increased 0.7%, while manufacturing rose 0.3% and utilities 3.5%. This provides evidence of continuing activity, but the utility contribution makes it unsafe to read the headline as a broad manufacturing boom. Capacity utilization remained below its long-run average. For industrial earnings, sustained customer orders and profitable use of capacity would matter more than extrapolating one preliminary month.
DIGITIMES
TSMC reports another record quarterly profit ↗
The public DIGITIMES earnings overview reports TSMC’s third-quarter profit rose 68.7% year on year, supported by advanced chips used in AI. That is tangible supplier earnings evidence. It does not establish whether every purchaser of computing capacity will earn an adequate return on its spending, or whether any particular stock valuation is justified. Suppliers and customers can occupy very different places in the same investment cycle.
Kiplinger
Technology shares weaken as AI spending faces scrutiny ↗
Kiplinger reports Friday declines of 2.1% for the Nasdaq and 1.1% for the S&P 500 amid continued semiconductor weakness and scrutiny of AI spending. It places the 10-year Treasury yield near 5.089%. Those are observed market outcomes, not a diagnosis of an inevitable crash. Higher required returns can reduce the present value investors assign to distant profits. The report also describes shifting October policy expectations during Fed remarks; that dated observation cannot establish expectations at this edition’s cutoff.
Reuters via Euronext
Oil falls after Russian sanctions waiver; shipping risks persist ↗
Reuters reports Brent futures fell 2.08% to $107.57 a barrel at 06:19 GMT Monday after the US waived new Russian sanctions and tariffs, while Gulf shipping disruptions persisted. This is a timed futures observation, not a later closing price. More available fuel could ease transport costs and household pressure, but policy permission does not itself deliver physical barrels. Sustained supply improvement would be more important for margins and inflation than a single relief move.
Reuters via MarketScreener
China growth improves while domestic demand remains uneven ↗
Reuters reports China’s third-quarter GDP grew 4.5% year on year, above the prior quarter and its 4.4% poll. September retail sales grew only 1.1%, while property investment continued contracting sharply. The combination suggests industrial and export resilience without confirming a broad household recovery. For companies selling into China, exposure to factories, consumers or property could therefore produce very different revenue outcomes. A headline GDP beat does not resolve those differences.
A three-card reflection
01Backdrop
Four of Wands
Upright
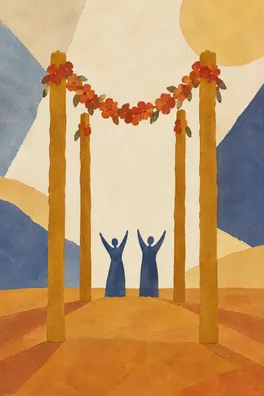
The upright Four of Wands represents a foundation, shared support and a milestone that deserves recognition. In the Backdrop position, it invites us to identify what is actually holding the economy up. The industrial-production release and TSMC’s results offer concrete examples of activity and realized earnings. They support a measured judgment that productive capacity and demand have not simply vanished because technology shares have fallen. The card supplies the image of a foundation; the reporting supplies the evidence.
A foundation can be uneven. Manufacturing grew more slowly than total industrial output, and strong earnings at a chip supplier do not measure the returns its customers will eventually earn. China’s growth composition adds another reminder that industrial strength can coexist with cautious households. My view is that these facts support continued scrutiny of business fundamentals, while giving too little basis for a broad claim that equities are inexpensive or that all demand is healthy. The evidence here does not show how much optimism or pessimism individual share prices already contain.
For a reader who feels pressure to celebrate every promising headline, the useful ritual is to record a genuine milestone precisely: a reported result, its period and the business it describes. Then write what it leaves unanswered. Sharing that distinction with a thoughtful reader can create the belonging this card evokes without making agreement the price of admission. The blind spot is treating a familiar investment community as proof that its story is correct; a supportive group should make dissent easier.
02Pressure point
Eight of Pentacles
Reversed
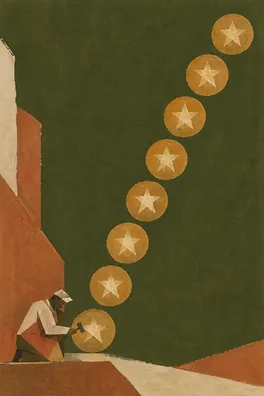
The reversed Eight of Pentacles brings quality, effort and purpose out of alignment. At the Pressure point, it focuses attention on the difference between spending heavily and creating durable value. AI infrastructure may generate current sales for suppliers while its buyers still need to turn that capacity into revenue and cash. This is an economic question about returns on invested resources, not a verdict delivered by the card. Strong supplier profit and investor unease can coexist without either fact cancelling the other.
Financing adds a second channel. When borrowing is expensive, projects need stronger eventual cash generation to justify their cost. Higher yields also increase the return investors can seek elsewhere, which can put pressure on the price paid for future equity earnings. Businesses able to fund investment internally may face different constraints from those reliant on repeated borrowing. We do not have company-by-company financing schedules, current valuation measures or a complete earnings-expectations dataset here, so it would be overconfident to label an entire sector safe or broken.
The reversal also describes an investor’s research trap: careless conclusions at one extreme, endless detail without a decision standard at the other. Before the next earnings report you read, choose a small set of questions about revenue quality, operating costs and the cash required to sustain growth. Set a stopping time and ask a reliable person which assumption deserves challenge. More screen time is not automatically better analysis. If the answers remain unavailable, record that gap instead of filling it with either FOMO or certainty that a bubble must burst.
03Grounded response
Nine of Swords
Reversed
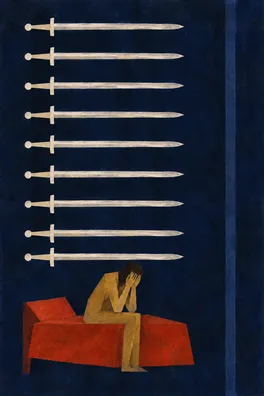
The reversed Nine of Swords can describe worry becoming speakable and beginning to ease, or fear becoming more hidden. In Grounded response, that ambiguity matters. Relief in oil futures can feel like permission to dismiss every risk; a falling technology index can feel like confirmation that every feared outcome has arrived. Neither emotional shift establishes the path of earnings, inflation or supply. The reflective task is to notice whether new information is changing your understanding or merely changing the intensity of your feelings.
Take one specific worry to a trusted person and ask for a defined form of help: listening while you distinguish an observed fact from a conditional scenario, for example. Write three separate lines for the event, its possible economic channel and the evidence still missing. If the concern is energy, separate the announced waiver from actual fuel availability and from a business’s ability to pass costs to customers. This gives the worry an assessable shape without pretending that uncertainty can be eliminated.
Choose scheduled information checks that fit your responsibilities and time horizon, and pause when repeated checking produces no new evidence. A quieter feed is useful only if you still review material developments; avoiding information altogether would fit the more hidden side of this reversal. After a discussion or a pause, notice whether you can name a condition that would change your view. That is a more useful sign of perspective than feeling completely calm or finding someone who shares your fear.
The financial view is cautiously discriminating: productive activity and supplier earnings provide support, while inflation, energy vulnerability and costly capital make the durability and financing of growth central questions. A short-term rebound in confidence would not by itself improve cash generation. Equally, a selloff would not by itself show that the real economy has stopped expanding. The Four of Wands asks what deserves confidence; the reversed Eight of Pentacles asks whether the work earns its cost; the reversed Nine of Swords asks whether our method leaves room to think.
A more supportive interpretation would gain strength from lasting improvements in physical fuel supply, broader easing of price pressures and earnings disclosures that connect investment to customer demand and cash generation. It would weaken if disruptions persist, costs spread into margins and household spending, or businesses need increasing finance without clearer returns. The competing explanation deserves attention: current investment could eventually improve productivity enough to support stronger earnings. These sources cannot establish its timing, scale or what investors already price in. Both the productive potential and the financing burden belong in the analysis.
For the coming week, keep a short evidence journal at one chosen review time. Record one fact, one proposed transmission into revenues, costs or valuation, and one observation that would challenge your interpretation. Add the emotion that made the headline compelling: fear of missing out, fear of loss or satisfaction at being proved right. Ask a trusted person to challenge the causal link rather than predict a price. Adjust the exercise if it becomes repetitive monitoring: the goal is clearer standards and a manageable information rhythm. Which assumption would you find hardest to revise if the next piece of evidence contradicted it?
A question to take with you
When a market headline feels urgent, what evidence would distinguish a change in business fundamentals from a change in my own fear or excitement?