Weekend market reflection
Oil, inflation and AI financing: resilience needs more than a reassuring headline
Investment offers economic support, but rising costs and financing doubts complicate the earnings outlook. A reflection on separating durable progress from market applause.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 18, 2026 at 7:00 AM · New York
U.S. Bureau of Labor Statistics
US import prices rise beyond fuel ↗
The Bureau of Labor Statistics reported September import prices up 1.1% on the month and 8.1% over a year, with nonfuel prices also rising. This is evidence of cost pressure extending beyond fuel, rather than a measure of October conditions. My interpretation is that import-dependent businesses face a choice between accepting narrower margins and raising prices, potentially weakening sales volumes. How much reaches customers depends on contracts, competition and demand; the release alone cannot tell us how much earnings will fall.
Reuters via MarketScreener
Warsh sees resilience but gives no rate-path preview ↗
Reuters reported that Warsh saw broadening investment supporting growth while adding near-term inflation pressure, and offered no preview of the next rate decision. The report described expectations of an October pause and a December increase. Those expectations can change. My reading is that strong investment can support supplier revenues before productivity gains lower costs, leaving the Fed with competing pressures. A pause would not by itself establish an easier financing environment or remove the risk that higher rates reduce the value investors place on future earnings.
Reuters via MarketScreener
Oil rises as supply concerns persist ↗
Reuters reported Friday Brent futures settling at $109.86 and WTI at $101.41 amid concerns over energy supply. It also described efforts to release reserves. The observed price rise and the proposed relief measures are distinct facts; neither establishes the duration of the disruption. If expensive fuel persists, transport costs and household essential spending could rise, squeezing discretionary demand and some companies' margins. More reliable supply would weaken that concern. A geopolitical risk premium can change rapidly even before physical supply or company earnings change.
Reuters via StreetInsider
Exxon signals a refining lift with upstream offsets ↗
Exxon signaled a possible $4.5 billion sequential refining earnings benefit alongside a $1.3 billion upstream price headwind, according to Reuters; full results were still pending. The report observed a rise of less than 1% in premarket shares. Refining earns the difference between product sales and costs including crude feedstock, so a crude-price headline does not describe the whole business. This preliminary update illustrates unequal effects across business lines, not a general improvement in household purchasing power or a completed earnings result.
Reuters via AOL
Canadian steel finds partial domestic support ↗
Reuters found that Canadian infrastructure and industrial projects, with government support, were helping some steelmakers adapt to constrained US access, while improvement remained uneven. The economic channel is local orders supporting plant activity, jobs and suppliers. The counterweight is that redirected demand may not replace lost export scale or remain equally strong across products and regions. For equities, project delivery, margins and dependence on policy support matter more than treating a national recovery story as proof that every producer benefits.
Reuters via MarketScreener
AI financing worries weigh on stocks as bonds find demand ↗
Reuters reported Friday declines of 1.09% for the S&P 500 and about 2.1% for the Nasdaq Composite, with AI-financing and interest-rate concerns weighing on technology. Treasury yields eased over the week even though they edged up Friday, and the dollar weakened. These are observed market reactions. My interpretation is that demand for government bonds can coexist with worry about corporate funding. A lower Treasury yield is therefore not automatic confirmation of stronger earnings or easier access to cash for a particular company.
A three-card reflection
01Backdrop
Five of Pentacles
Reversed
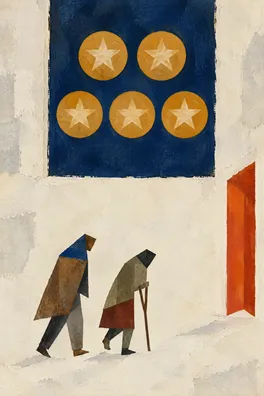
The reversed Five of Pentacles places rebuilding and available support in the Backdrop. Its meaning is movement out of scarcity, with foundations still being repaired. As a reflective lens, that fits the distinction between an economy finding sources of demand and one whose finances are fully secure. The investment and steel reports above offer examples of support, but the inflation evidence prevents us from treating support as universal relief. The card supplies no economic evidence; it asks us to examine where the evidence actually shows a bridge through difficulty.
In financial terms, new orders may help a business cover fixed costs, while higher input prices and financing expenses consume part of the benefit. A company can have an attractive project and still need cash before customers pay. Households likewise may see employment opportunities without feeling an improvement in what their income buys. These are conditional mechanisms, not claims that every business or household is in the same position. The quality, timing and accessibility of support matter as much as its announcement.
For the reader, scarcity thinking can make every negative headline feel like proof that recovery is impossible. Its opposite can make the first reassuring headline feel like complete rescue. Write down the specific support in a story, who receives it and what obligation or uncertainty remains. If the funding terms or actual order delivery are unknown, leave them unknown. Accepting an incomplete picture is a useful form of intellectual support when the urge is to force a confident verdict.
02Pressure point
The Sun
Reversed
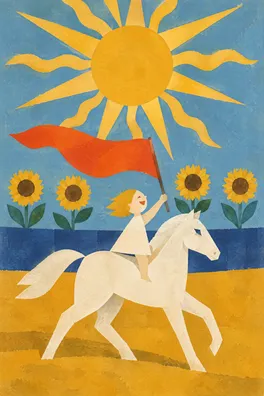
The reversed Sun, in the Pressure point, concerns confidence whose light is obscured, delayed satisfaction and difficulty recognizing what is already good. Here the tension is between visible economic ambition and the slower work of converting spending into dependable earnings. An investment boom can be real while its eventual returns remain uncertain. The reversal invites scrutiny of the gap without declaring that the whole undertaking has failed.
The financial risk is a mismatch of timing: cash must fund construction, equipment and interest before projects generate enough revenue. Liquidity means the capacity to meet payments as they come due; a valuable asset does not necessarily provide that cash today. Separately, valuations express what investors pay for expected future profits. Higher required returns can lower that present value even if a business continues growing. These mechanisms help explain why enthusiasm about technology and anxiety about financing can coexist. Friday's selloff establishes a change in prices, not the ultimate economic value of AI.
One blind spot is treating caution as sophistication and dismissing all productive investment. Another is assuming that a compelling long-term technology story answers every question about debt, customer demand and cash conversion. We do not have enough valuation or expectation data here to declare a sector cheap, expensive or fully repriced. When confirmation bias pulls you toward a favorite story, acknowledge one real strength and identify one unresolved detail that could undermine it. Delayed results deserve investigation; they do not automatically deserve either panic or optimism.
03Grounded response
Six of Wands
Upright
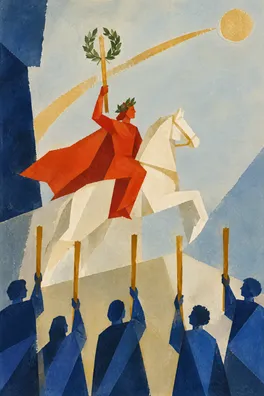
The upright Six of Wands brings visible results, recognition and support into the Grounded response. Its public dimension matters: market narratives reward winners quickly, and that applause can tempt a reader to borrow the crowd's certainty. In this position the invitation is to define what deserves recognition. A documented improvement in understanding, or a business meeting a previously stated milestone, is more informative than the feeling of joining the winning side.
Apply that distinction to the news by choosing evidence appropriate to the claim. A supply-relief story needs evidence of reliable deliveries. An investment story needs progress toward funded construction, paying customers and sustainable cash generation. A cost-pressure story needs company discussion of prices, volumes and margins. No single indicator settles all three. Recognize genuine progress when it appears, while retaining the conditions that would change your assessment. The card's success theme is a prompt for an accountable review process, never a forecast of market victory.
Fear of missing out often appears as a demand to react before the next price move; panic makes the same demand with a different emotion. At a planned information check, record the new fact, your interpretation and the evidence still missing in separate sentences. Then step away from repeated headline refreshes. Before any personal financial decision, revisit your own time horizon and capacity for loss rather than asking the day's popularity contest to define them. Thank a person or reliable source that helped you challenge an assumption; public support can improve judgment when it makes room for disagreement.
My qualified view is that cost and financing pressures deserve more weight than a simple story of broad recovery, while investment and selective industrial adaptation remain meaningful supports. This is an assessment of the economic balance, not a prediction of the next market session. Higher fuel and import costs can reduce spending elsewhere and compress margins; continued investment can sustain orders and employment. Which force dominates depends on duration, financing terms and the ability to turn demand into cash.
The strongest competing view is that supply relief and productive investment could absorb the shock more successfully than current anxiety suggests. That would become more persuasive with reliable energy flows, easing cost pressure and evidence that projects generate revenues without repeatedly needing more expensive funding. Persistent disruption, weaker sales volumes, margin erosion or funding difficulty would strengthen the cautious view. We do not know how much of either scenario is embedded in current equity prices. The reported bond buying and technology selling show shifting preferences, not a complete measure of expectations.
The cards trace a reflective movement from incomplete support, through obscured confidence, toward progress that can be checked. They do not resolve the financial uncertainty. The reversed Five of Pentacles asks where support reaches the people or businesses that need it. The reversed Sun asks what enthusiasm or disappointment hides. The Six of Wands asks which achievements deserve recognition once we look beyond applause.
For the coming week, choose one economic claim you already feel strongly about. At one scheduled daily review, add a verified fact, its possible earnings or demand channel, and one observation that would change your view. Keep an emotional note alongside it: urgency, relief, fear or the wish to be proved right. If repeated checking adds only agitation, reduce the number of checks; if a material fact changes, update the reasoning explicitly. The experiment succeeds when you can revise a belief without treating revision as personal defeat.
A question to take with you
Which headline makes me feel I must react immediately, and what evidence would help me distinguish a change in sentiment from a change in the economic case?