Weekend market reflection
Resilient activity, fragile confidence: earnings under inflation pressure
Strong chip earnings and growing output support activity, while inflation and funding risks complicate equity valuations. A reading on separating financial evidence from the urge to react.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 17, 2026 at 7:00 AM · New York
U.S. Bureau of Labor Statistics
September inflation rises, led by gasoline ↗
The Bureau of Labor Statistics reported September consumer inflation of 0.6% for the month and 3.7% over the year. Gasoline accounted for more than half the monthly rise, while prices excluding food and energy also increased. My interpretation is that this combination complicates a simple story of temporary fuel inflation: households face a purchasing-power squeeze, and firms may face pressure on costs or demand. This release alone does not establish the next Fed decision or a recession.
U.S. Census Bureau
Retail sales rise in dollars, without adjustment for prices ↗
Census reported a 0.8% monthly increase in September retail and food services sales, with August revised higher. This is evidence of resilient dollar spending, but the figures do not remove price increases. A higher bill is not necessarily a larger basket. For consumer-facing companies, the important follow-through is whether sales volumes and profit margins remain healthy after costs. Subtracting the overall CPI from retail growth would not provide a precise real-sales measure because the two cover different baskets.
Federal Reserve Board
Industrial output grows with uneven components ↗
The Federal Reserve reported September industrial production up 0.7%, including a 0.3% manufacturing increase and a much larger utilities rise. Vehicle and parts output fell 3.0%. These preliminary figures support continued activity but show why the headline should not be treated as uniform strength. My conditional read is that industrial earnings can remain supported where actual orders and output persist; the uneven components leave room for company-specific disappointment and do not establish a broad manufacturing boom.
Reuters
Warsh sees resilient investment but gives no rate-path signal ↗
Reuters reported that Fed Chair Kevin Warsh described investment-led resilience and near-term demand arriving before AI productivity benefits. He did not preview the next rate decision. That timing matters economically: building capacity creates spending now, while efficiency gains may arrive later. If demand outruns available supply, inflation can persist and financing can remain restrictive. His optimism about future productivity is a policy-maker’s assessment, not proof of future earnings or a commitment to pause.
Reuters
TSMC posts record profit while planning cautiously for 2027 ↗
Reuters reported TSMC’s record quarterly profit, up 69% from a year earlier and above the cited analyst estimate, alongside a higher full-year revenue-growth outlook. The company also described caution toward consumer and price-sensitive markets in 2027. This supports a distinction between current AI supplier earnings and the health of every end market. Strong supplier results do not by themselves establish that customers’ future AI revenues will justify their spending, or that every related equity valuation is attractive.
Reuters
Dollar weakens as October hike expectations fade amid AI concerns ↗
In its Friday report, Reuters observed a weaker dollar, stabilizing Treasury yields and AI equity weakness accompanied by stress in parts of credit markets. Its cited futures snapshot put the chance of unchanged October Fed rates at 83%; that is changing market pricing, not a promise. The coexistence of calmer rate expectations and AI concerns matters: relief about the next meeting can support sentiment without solving questions about debt repayment and business returns. This report does not tell us how much of those risks each stock already reflects.
Reuters
Some Iranian fuel cargoes pass despite blockade; scale is limited ↗
Reuters reported evidence of limited Iranian LPG and jet-fuel shipments despite the blockade, with important disputes over tracking and what passage signifies. The volumes described were a fraction of former exports, and the report did not establish restored crude supply. I would therefore avoid treating these cargoes as confirmation that energy pressure has ended. For fuel-using businesses and household budgets, a durable improvement would require broader, sustained supply evidence; this article supplies no measured stock-market reaction to the shipments.
A three-card reflection
01Backdrop
Queen of Cups
Upright
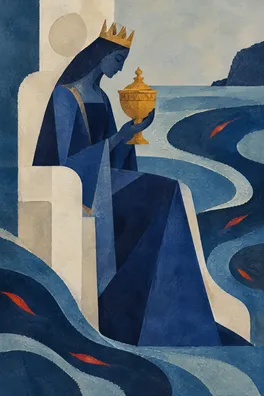
The upright Queen of Cups brings sensitivity and careful listening to the Backdrop position. As a reflective lens, she asks us to understand how the same economy can feel very different to a household paying for fuel and a business benefiting from investment spending. The inflation and retail releases describe prices and dollar sales; they cannot tell us that every family is comfortable. Attending to that distinction improves financial reasoning because household room to spend eventually matters for company demand.
My qualified view is that the evidence supports resilience with meaningful strain, rather than confidence in an easy expansion. Growing production and strong chip earnings are supportive, but neither cancels the possibility that costs squeeze other businesses. An energy-intensive firm unable to pass costs on could lose margin; one that raises prices might preserve margin but lose customers. These are conditional channels, not reported outcomes for particular companies.
The Queen’s empathy is useful when it makes us curious about those differences. Its blind spot would be absorbing everyone’s anxiety and mistaking that emotional intensity for evidence of universal deterioration. If alarming commentary makes you feel that you must act immediately, first write down whose experience is being described and which financial variable it could change. When discussing the news with someone close to you, ask whether they want help understanding it or simply company. Listening does not require adopting their market conclusion.
02Pressure point
Wheel of Fortune
Upright
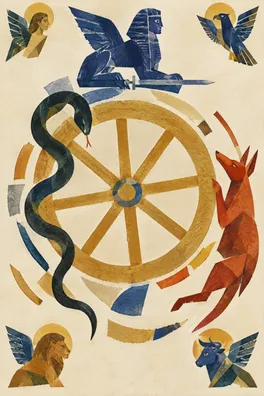
The upright Wheel of Fortune, in Pressure point, reflects cycles and external forces that can change an otherwise convincing story. Its possibility of a favorable opening is not evidence that markets are about to rise. Here the useful tension is between an investment cycle producing earnings today and the financing and customer economics needed to sustain it. TSMC’s results support the first part; concerns about AI borrowers leave the second unresolved.
A valuation is the price investors assign to expected future business returns. Even if current profits improve, a stock can face pressure when investors demand a higher return for uncertainty, or when financing costs reduce future cash available to owners. Conversely, confidence can recover before a slower economic improvement is visible. The reported shift toward expecting an October pause illustrates how quickly the policy story can turn, without proving that inflation or borrowing costs have been durably resolved.
This is fertile ground for FOMO and confirmation bias. After seeing a strong earnings headline, you might search only for reasons that the investment boom will continue; after a selloff, you might read the same caution as proof of collapse. Put both explanations beside each other. Continued orders, cash generation and customers earning returns on their spending would strengthen the constructive case. Cancellations, deteriorating margins or financing difficulties would weaken it. The Wheel invites adaptability: revise the explanation when evidence changes, without turning every change in price into a new economic regime.
03Grounded response
Eight of Wands
Reversed
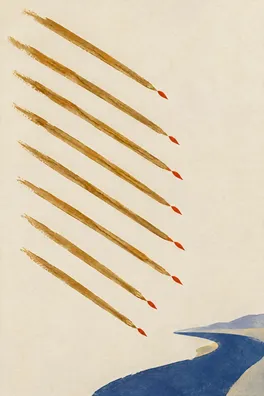
The reversed Eight of Wands describes delay, scattered messages and haste that disrupts coordination. In Grounded response, it suggests that a crowded information stream may be moving faster than your understanding. This is a reflection on decision habits, not a prediction of delayed economic news. A headline about inflation, a later comment about the Fed and a report about AI credit can each be accurate while referring to different times and mechanisms.
Gather one important claim into a clear record: what happened, when the source observed it, how it might affect earnings or financing, and what remains an assumption. For example, the reported October pause probability concerns one meeting. Turning it into a conclusion that money will soon become cheap adds an unsupported step. Similarly, limited fuel shipments do not demonstrate that a supply disruption is over. A few minutes spent checking those links can prevent an emotionally appealing narrative from outrunning its evidence.
Set a specific time to revisit the record after relevant evidence arrives, and let that appointment replace repeated checking of the same prices. Before any financial decision, reconnect with your own time horizon and capacity to absorb uncertainty. The alternative reading matters too: slowing down can become avoidance. If there is a real deadline, identify the missing information you can actually obtain and a time to review it. Clarity should make a considered process possible, not demand impossible certainty.
The three cards move from listening to the economy’s uneven experience, through recognition that cycles and expectations can shift, toward a more coordinated response to information. They do not establish the financial view. The releases and reporting support a narrower judgment: present activity has real sources of strength, while inflation and the economics of funding investment remain credible constraints on earnings and valuations.
In a more constructive scenario, investment keeps supporting orders, customers begin turning that capacity into durable income, and easing cost pressure allows profits to broaden. That would make resilience less dependent on a narrow set of suppliers. In a less constructive scenario, persistent costs restrain household demand while borrowers struggle to earn enough to service investment-related debt. A calmer expectation for one Fed meeting would not remove that combination. We lack a complete valuation and expectations picture, so neither scenario establishes how much upside or downside is already reflected in prices.
For the coming week, try a short journal with three columns: verified fact, financial implication, and evidence that would change my view. Add one line naming the emotion the story triggers. If it is fear of missing out, look for the cost or funding assumption you are overlooking; if it is panic, look for evidence of continuing demand you may be dismissing. Choose a limited review window rather than reopening the same story whenever anxiety rises.
At week’s end, notice whether your explanation changed because new evidence arrived or because the emotional tone changed. Adjust the practice if the review window misses genuinely important information, or if the journal becomes a way to collect only supporting arguments. Which assumption deserves a clearer test before you let it guide your next decision?
A question to take with you
When a headline makes me want to react, what am I assuming about earnings, financing or expectations, and what specific evidence would make me reconsider?