The market mirror
Inflation, financing costs and the test of durable earnings
Hotter inflation pressures valuations while energy disruption tests margins. A reading on distinguishing resilient earnings from reassuring headlines, and replacing panic with consistent evidence.
· AI-assisted readings from randomly drawn cards. For reflection and entertainment.
The news behind this reading
News snapshot · October 15, 2026 at 7:00 AM · New York
Reuters
Inflation surprise lifts rate concerns and pressures US stocks ↗
Reuters reports that September core consumer prices rose 0.3% over the month, above the 0.2% forecast. The S&P 500 closed 1.11% lower and the Nasdaq 1.88% lower; the two-year Treasury yield ended at 4.81%. These are observed data and reactions, not proof of the next market move. Higher required returns can reduce what investors pay today for distant earnings, while more expensive borrowing can constrain investment. The late-session report put October rate-hike odds around 33%, up from roughly 20% before the release: policy expectations moved, but a hike was far from certain.
Reuters
Morgan Stanley profit beats estimates, with divergent trading results ↗
Morgan Stanley's results offer a useful counterweight to a uniformly gloomy story. Reuters reports that equity trading revenue rose nearly 41%, while fixed-income trading revenue fell 7.3%. Volatility can generate trading activity and fees even while making bond inventories harder to manage. This is evidence of different earnings channels within one institution, rather than proof that all banks or their borrowers are thriving. The quality and repeatability of revenue matter more than a single headline profit beat.
Associated Press
IEA cuts oil demand outlook as energy disruption strains growth ↗
AP reports that the IEA cut its oil demand outlook, citing costly fuel, limited supplies and a deteriorating economic outlook. The agency's projected demand decline is a forecast, not an observed full-year outcome. A supply squeeze can raise transport and production costs while reducing the spending power left for other purchases. Lower consumption under those conditions would signal strain rather than uncomplicated inflation relief; improved physical supply would be a different, more supportive explanation for any subsequent price easing.
Associated Press
China export surge coexists with weak domestic demand ↗
AP reports that China's September exports rose 36.3% from a year earlier and imports rose 31%, alongside a $133.5 billion surplus. Strong shipments coexist with weak domestic consumption and investment. For businesses exposed to global trade, export activity can support orders, while competitive pressure and possible trade restrictions can complicate margins and planning. These figures alone do not establish the strength of US final demand, and rising imports should not be ignored when assessing the imbalance.
Reuters
IMF urges fiscal adjustment as borrowing costs rise ↗
Reuters reports the IMF's call for US tax or spending adjustments because growth alone would not address debt quickly enough. This is policy advice, not an enacted budget change. If credible fiscal measures reduce financing concerns, they could ease pressure on longer-term borrowing costs; their composition could also restrain near-term demand. Neither implementation nor that market response is established. Government borrowing and private investment can therefore remain competing influences on financing conditions.
Reuters
Waller offers a growth-based explanation for higher yields ↗
Before the latest CPI release, Fed Governor Christopher Waller argued that higher yields reflected real growth, AI investment and debt-related factors, rather than unanchored inflation expectations, Reuters reports. That interpretation deserves consideration without treating it as settled fact. Growth-driven borrowing can accompany stronger earnings, whereas an inflation or risk premium raises financing costs without the same benefit. His distinction between present investment demand and later productivity gains also cautions against assuming immediate efficiency improvements will offset current costs.
A three-card reflection
01Backdrop
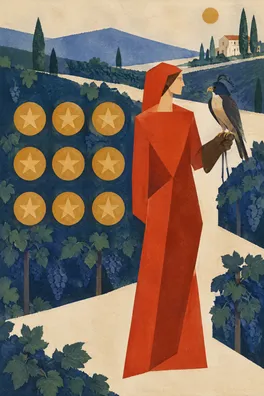
Nine of Pentacles
Upright
The upright Nine of Pentacles places earned comfort and independence in the Backdrop. As a reflective lens, it asks what actually sustains economic resilience: dependable cash generation, useful investment and enough room to absorb higher costs. It does not establish that those conditions prevail. In this news setting, its emphasis on maintaining what has been built encourages a closer look at the foundations beneath an attractive growth narrative.
The financial tension is that an investment boom can support current orders and employment while placing demands on funding before its benefits arrive. A business with reliable customer receipts may handle that interval differently from one dependent on repeated refinancing. Likewise, rising nominal sales can conceal weaker margins if input and interest costs rise faster. Those are questions to investigate in company disclosures, not conclusions supplied by the card or this snapshot.
For a reader who fears missing the next growth story, the card's idea of sufficiency is practical. Write down which features of your own routine provide real stability, then name the evidence needed to distinguish productive expansion from expensive appearance. Allow yourself to value an existing habit of patient review. The blind spot is complacency: enjoying what has been built should not become a reason to dismiss changing costs or assume earlier success makes every new commitment sound.
02Pressure point
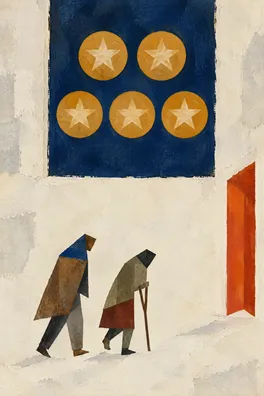
Five of Pentacles
Reversed
The reversed Five of Pentacles brings recovery, available support and the rebuilding of resources into the Pressure point. Reversal here suggests emerging from scarcity rather than complete security. Its relevance is the temptation to treat any encouraging result as confirmation that a difficult financing environment has been overcome. Morgan Stanley's contrasting trading businesses show why recovery and vulnerability can exist together; one favorable income stream does not settle the condition of the whole system.
My qualified view is that the financing and cost pressures deserve more weight than a reassuring headline alone, while the evidence does not justify declaring a broad earnings collapse. Costly energy can squeeze household discretionary spending and business margins at the same time. Higher rates may slow demand, but cannot themselves restore disrupted fuel supply. Firms able to pass through costs may protect margins differently from firms whose customers are already stretched; actual volume, pricing and funding disclosures would help distinguish the cases.
Scarcity anxiety can push an investor in opposite directions: panic at a red screen, or urgent pursuit of a rebound to repair a felt loss. Name which impulse is present before consuming more commentary. Seek support for a specific gap in understanding, such as how a company's debt comes due, rather than asking someone to validate an entire outlook. Accepting that help fits the card's rebuilding meaning. An alternative reading is that resources are genuinely improving; remain open to that possibility, but ask for sustained evidence instead of treating relief as completion.
03Grounded response
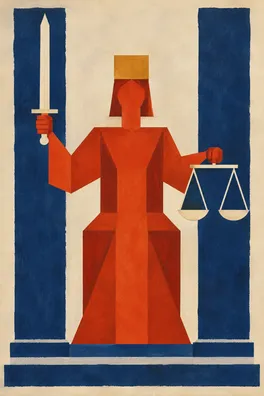
Justice
Upright
Upright Justice makes the Grounded response a matter of facts, consequences and consistent standards. It asks you to weigh the same kind of evidence when it challenges your view as when it supports it. The card supplies no verdict on equities. Its usefulness is procedural: the explanation for a price change, the condition of a business and your emotional reaction to both need separate entries in the journal.
Start with three short columns: reported fact, possible transmission, and unresolved assumption. For example, a hotter inflation release is a fact; pressure on valuation through higher required returns is a mechanism; the claim that a particular share price already fully reflects that pressure remains unproven here. Valuation means the price investors are willing to pay for earnings or cash flows. A daily loss can reflect changed expectations well before earnings change, and a subsequent bounce would not by itself demonstrate that the underlying cost problem has disappeared.
Before reading another opinion, add one relevant fact and one competing explanation. If your first account is inflation-driven distress, consider Waller's growth-based account of yields; if your first account is unstoppable investment-led growth, examine funding needs and the delay before productivity gains. Limit repeated price checking to a schedule you can follow and revisit your own time horizon and capacity for uncertainty. Justice's blind spot would be false precision: a neatly organized table cannot remove missing information, and consistency should allow a reasoned change of mind.
The spread moves from resources worth maintaining, through an incomplete rebuilding process, to accountable judgment. The Nine of Pentacles asks whether apparent prosperity rests on durable foundations; the reversed Five of Pentacles keeps attention on uneven recovery; Justice asks what evidence could fairly distinguish resilience from wishful thinking. These are prompts for examining the economic argument, never evidence for it.
The present financial balance looks more demanding for valuations and margins than the growth narrative alone suggests. Inflation can keep financing costs elevated, and disrupted energy supply can weaken spending power while raising business expenses. At the same time, strong activity in parts of financial services and an investment-led explanation for yields prevent a simple conclusion that demand and earnings are uniformly deteriorating. Near-term sentiment can change with each policy headline; the slower fundamental question is whether cash flows and useful investment returns can keep pace with their costs. This snapshot does not tell us how much of that tension individual securities already price in.
The cautious view would strengthen if broader cost pressures persisted alongside weaker sales volumes, worsening margins or more difficult refinancing. It would weaken if physical energy availability improved, underlying price pressure eased and companies demonstrated resilient cash generation without relying on increasingly costly funding. Lower yields would also need interpretation: relief from inflation and supply stress would mean something different from falling yields caused by sharply weaker demand. No single indicator resolves all these channels.
For the coming week, choose one financial claim you keep encountering and record its strongest support, its best alternative explanation and the next evidence that could change your assessment. Review the entry at a planned time instead of rewriting it with every price notification. Note whether the urge to react arose from FOMO, fear of loss or a substantive new fact. If your information schedule leaves you uninformed about a material development, adjust the sources or timing; if it merely feels uncomfortable to wait, examine that discomfort first. What assumption are you currently protecting more carefully than you are testing it?
A question to take with you
Which piece of evidence would genuinely change my financial view, and which market emotion makes me least willing to look for it?